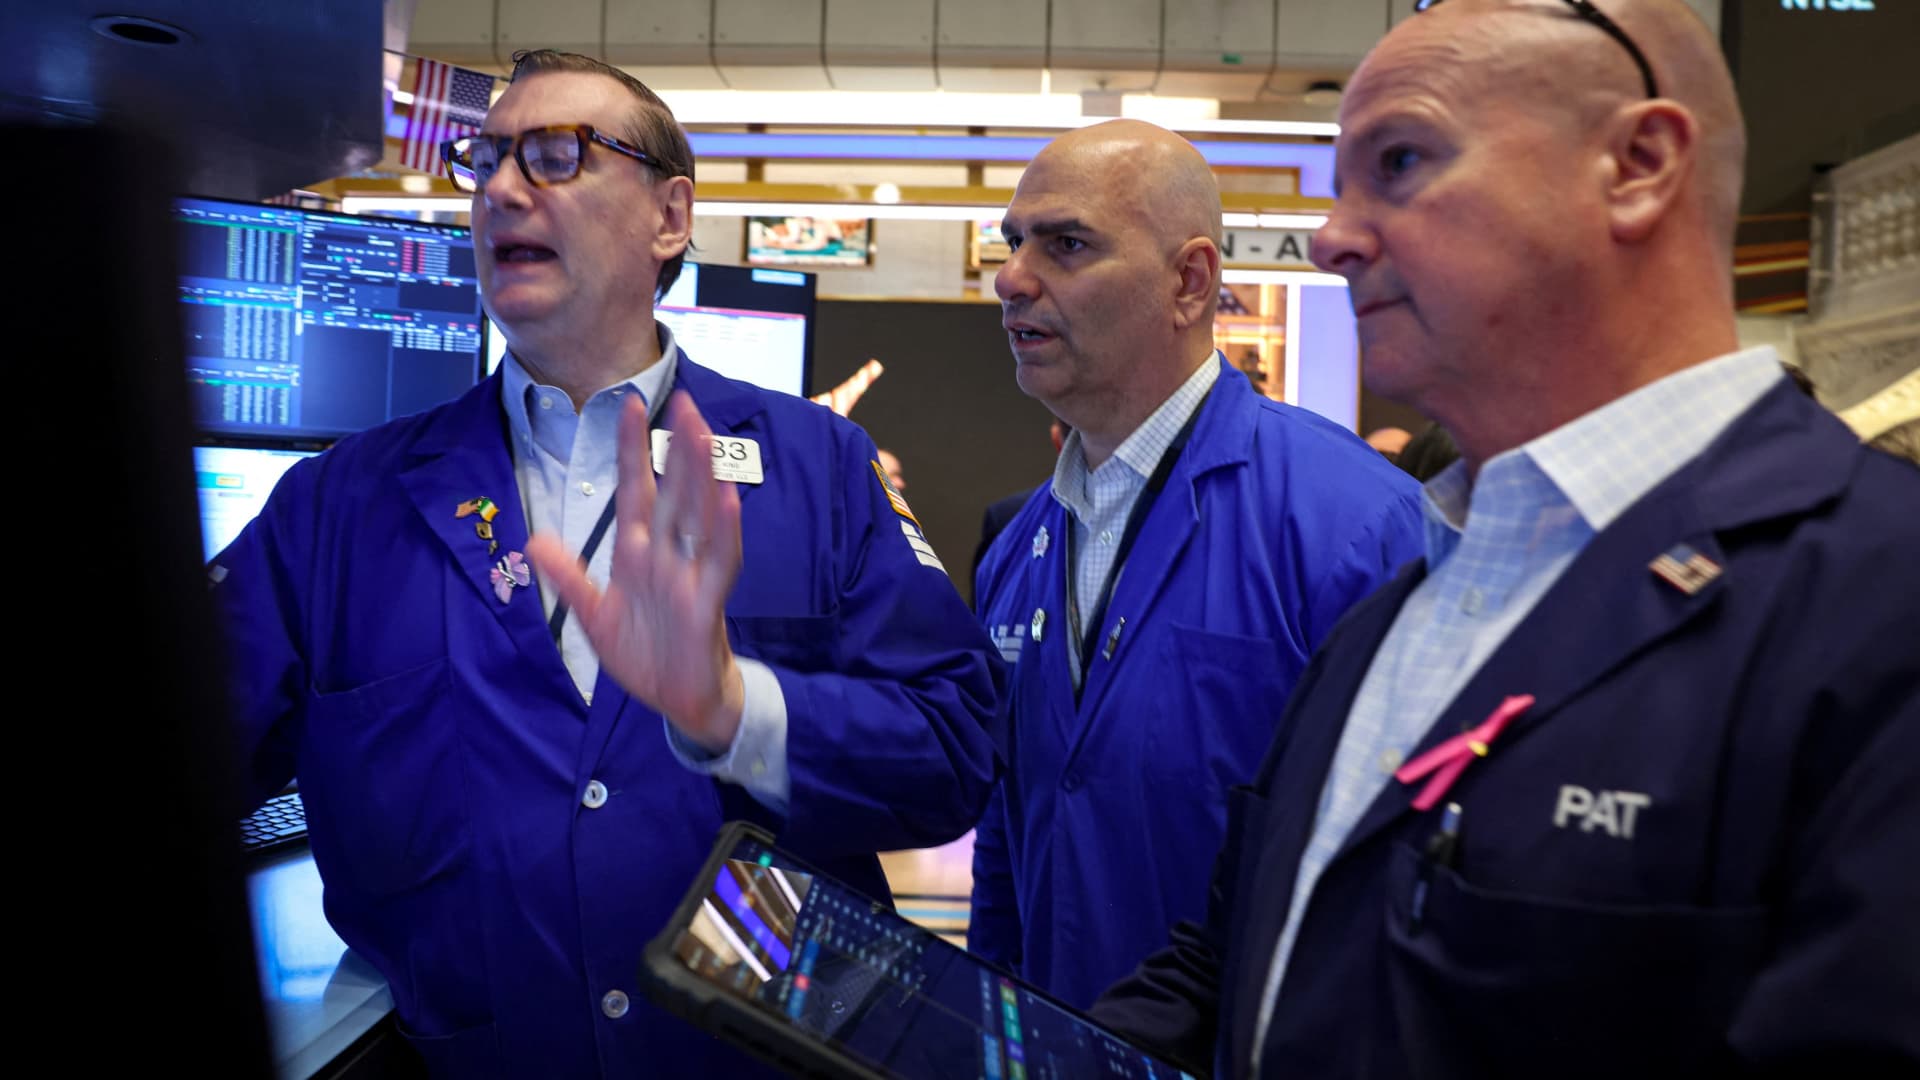


Before this week's Federal Reserve interest rate decision, Wall Street is discussing a less common scenario: if the Fed chooses to raise rates, U.S. stocks might not fall but instead rise. What the market is more concerned about at present is the resurgence of inflation and the continued upward pressure on valuations caused by rising long-term U.S. Treasury yields.
Interest rate hike expectations are heating up rapidly
After last month's Jackson Hole Symposium, Federal Reserve Chairman Kevin Warsh sent a strong signal regarding inflation. Subsequently, the released inflation data indicated a heating trend, and rising oil prices also prompted the market to quickly raise expectations for a rate hike in September.
According to the CME FedWatch tool, the probability of the federal funds rate rising to the range of 3.75% to 4.00% after this Wednesday's decision has reached 90%. Federal funds futures pricing also indicates that market expectations for further interest rate hikes in October and December have significantly increased.
Market focus shifts to long-term interest rates
Normally, interest rate hikes raise financing costs and lower the valuation of future profits, which is detrimental to the stock market. However, this time, traders are more concerned about whether long-term government bond yields will continue to rise.
On Monday, the yield on 10-year U.S. Treasury bonds briefly rose to 5%, marking the first time it has reached this level since 2023. At that time, the main U.S. stock indices also fell, indicating that rising long-term interest rates remain a direct source of pressure on the current market.
Some institutions believe that if the Federal Reserve raises interest rates at this time and continues to emphasize its determination to curb inflation after the meeting, it may actually help stabilize the long-term yield curve. Horizon Chief Investment Officer Scott Ladner stated that what is truly crucial is the policy signal and its net impact on long-term interest rates, which is also where the current market structure differs from in the past.
Tough stance or alleviation of stock market pressure
The key focus for the market next is not only whether there will be an interest rate hike but also the wording used by Walsh at the press conference. If he continues with the tough stance he adopted at Jackson Hole in August, the market may further anticipate the subsequent interest rate hike path in advance.
American Bank interest rate strategist Mark Cabana predicts that in this scenario, the yield on 2-year U.S. Treasury bonds could rise by 5 to 10 basis points, while the yield on 30-year bonds might fall by a similar amount. He believes that the choice faced by the Federal Reserve at its September meeting is relatively straightforward: either raise interest rates or risk a sharp increase in long-term U.S. Treasury bond yields.
From historical experience, after a new round of interest rate hikes begins, the stock market often faces pressure. Statistics from Canaccord Genuity show that in the past 30-plus years, during 6 rounds of tightening cycles, the S&P 500 index has averaged a decline of 3.4% in the month following the first interest rate hike, and its performance has also been weak in the following two to three months.
However, JPMorgan strategist Mislav Matejka believes that most of the repricing of bond yields may have already occurred. If the market believes that the Federal Reserve will continue to curb inflation rather than let it get out of control, then the pressure on the bond market is expected to ease, which could also create room for a further rebound in U.S. stocks before the end of the year.