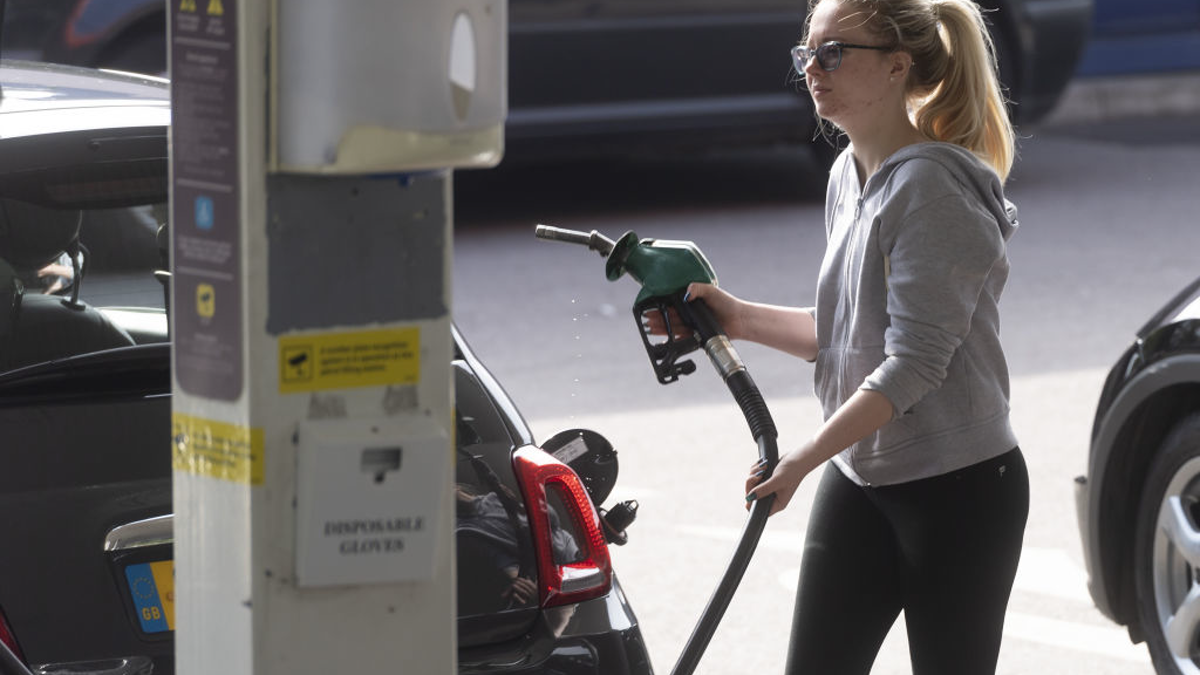On September 16, the Office for National Statistics (ONS) in the UK announced that in August 2026, the Consumer Price Index (CPI) CPI rose by 3.1% year-on-year, higher than the 2.9% in July; the index including the cost of own housing CPIH also rose by 3.3% year-on-year, exceeding the previous month's 3.1%. Both indices saw a 0.5% increase month-on-month, compared to a 0.3% increase in August 2025. The main factor driving annual inflation upwards was transportation, particularly car fuel costs. Meanwhile, the core CPI CPI remained at 2.6% year-on-year, and the core CPIH also stayed at 2.9%; there was no acceleration in the rise in service prices either. The overall index has rebounded significantly, but the pressure is mainly concentrated on goods and energy sectors.
Diesel fuel rose by 14.2 pence in a month, with energy once again becoming the focus of the inflation narrative.
In August, the average price of diesel increased by 14.2 pence per liter, reaching 181.8 pence; a year ago at the same time, it only rose by 0.8 pence. Both gasoline and diesel contributed to a year-on-year increase in automobile fuel prices of 23.0%, which is higher than the 15.5% increase in July. Annual inflation compares changes between this year and the same month last year; therefore, when energy prices surge this year and the base figure from last year is relatively mild, the impact is quickly magnified.
Transportation categories are also affected by air ticket prices. From July to August, air ticket prices increased by 6.2%, compared to 2.1% during the same period last year, with long-distance routes experiencing a greater increase. However, vehicle maintenance costs and railway ticket prices partially offset this rise. Within a single category, the trends are not consistent; therefore, it cannot be simply assumed that all transportation expenses for residents increased at the same rate, which is indicated by the 3.1% increase mentioned as CPI.
Housing and household services saw a year-on-year increase of 4.3%, higher than the 4.1% in July. The cost of owning a home rose from 3.7% to 3.9% year-on-year, and there were also increases in the prices of household heating oil and some fixed-rate electricity services. By including the cost of owning a home, CPIH provides a more comprehensive reflection of household living expenses than CPI, which also explains why the annual increase in CPIH was 0.2 percentage points higher.
Food and non-alcoholic beverage inflation remained at 1.3%, not accelerating along with energy prices. For low-income families, the weight of food, housing, and energy costs is higher, so their perceived inflation may still be significantly higher than the overall index. An increase in the inflation rate indicates that price levels continue to rise more rapidly, but it does not mean that all goods are increasing in price at the same time, nor does it mean that previous price increases have reversed.
Core indicators provide another clue. Excluding energy, food, alcohol, and tobacco, the core CPI year-on-year rate was 2.6%, the same as in July; the core CPIH was 2.9%, also remaining unchanged. CPIH commodity inflation rose from 2.2% to 2.7%, while service inflation remained at 3.6%. This indicates that the increase in August mainly came from commodities and energy, and the more persistent pressure of service inflation did not worsen further during that month.
For the Bank of England, the energy shock cannot be ignored, nor can it be equated with overheated demand.
The most difficult aspect of monetary policy to manage is external energy prices. Raising interest rates cannot increase crude oil supply, nor can it directly lower international fuel prices; however, the impact of energy prices spreads through transportation, production costs, and inflation expectations. If businesses continue to pass on these costs to consumers, and employees demand compensatory salary increases, a single energy shock could affect core and service prices. Central banks need to assess these secondary effects, rather than merely reacting mechanically to one-month changes in the overall CPI.
Service inflation at 3.6% and wage growth rates remain key areas of focus. Labor market data from the previous day indicated a decline in job vacancies and more modest wage growth in the private sector, which helps to limit demand-driven pressures. However, real wages, employment, and consumption have not weakened comprehensively, and central banks cannot assume that service prices will automatically return quickly to near their targets.
The figures for August also include a base effect. The year-on-year increase in fuel prices depends not only on current prices but also on the trajectory during the same period last year. If oil prices remain stable in the future, the annual contribution may gradually change; however, if international energy prices and exchange rates continue to drive up import costs, commodity inflation may remain high. To determine the trend, data from several consecutive months is required, rather than regarding 3.1% as a new permanent level.
Enterprises need to distinguish between direct and indirect exposures. Industries such as logistics, aviation, chemicals, and high-energy-consuming sectors will be the first to feel the impacts of changes in fuel and electricity prices, while retail and service companies will be indirectly affected through transportation contracts, supplier quotes, and employees' commuting patterns. Fixed-price contracts may delay the transmission of these price changes, leading to a time mismatch between official indices and corporate bills.
Family responses also have a reverse effect on the economy. Rising expenses for fuel and housing squeeze discretionary spending, which may weaken demand in retail, dining, and leisure industries. If consumers reduce their expenditures, companies' ability to pass on costs will decrease; if incomes can still cover the price increases, inflation may last longer. Therefore, the rise in overall inflation and the strength of economic demand cannot be inferred in the same direction.
The market will also compare CPI with CPIH. The inflation target in the UK is usually expressed as CPI, but CPIH includes the cost of owning a home, which is closer to the total household expenses. Both rose by 0.2 percentage points in August, indicating a consistent direction; the difference comes from the scope of coverage, rather than any conflict between the two sets of data. When analyzing residential pressures, one should look at CPIH, and when analyzing policy targets, one should look at CPI to avoid using the wrong indicators.
Long-term inflation expectations also deserve attention. A sudden increase in fuel prices is quickly perceived by the public, and if households and businesses believe that energy costs will continue to rise, wage negotiations and contract pricing may be adjusted in advance. It is this process of shifting from visible prices to actual behavior that central banks are concerned about. The current stability of key indicators indicates that the impact is not yet significant, but this does not mean that the subsequent months can be ignored.
The figures from the National Statistics Office represent officially released estimates, but subsequent policy decisions will still need to take into account September's data on prices, wages, employment, and business surveys. The most accurate summary for August is that energy costs pushed the UK CPI back above 3%, while core and service indicators have not yet accelerated accordingly. This has increased inflation risks, but it has not yet been proven that there is a new round of widespread overheating in domestic demand.