IT News from October 15th: Jiangbolong has released its performance forecast report for the third quarter of 2026 (January to September 2026) today:
Total operating revenue: 38 billion to 40 billion yuan, a year-on-year increase of 127.08% to 139.03%
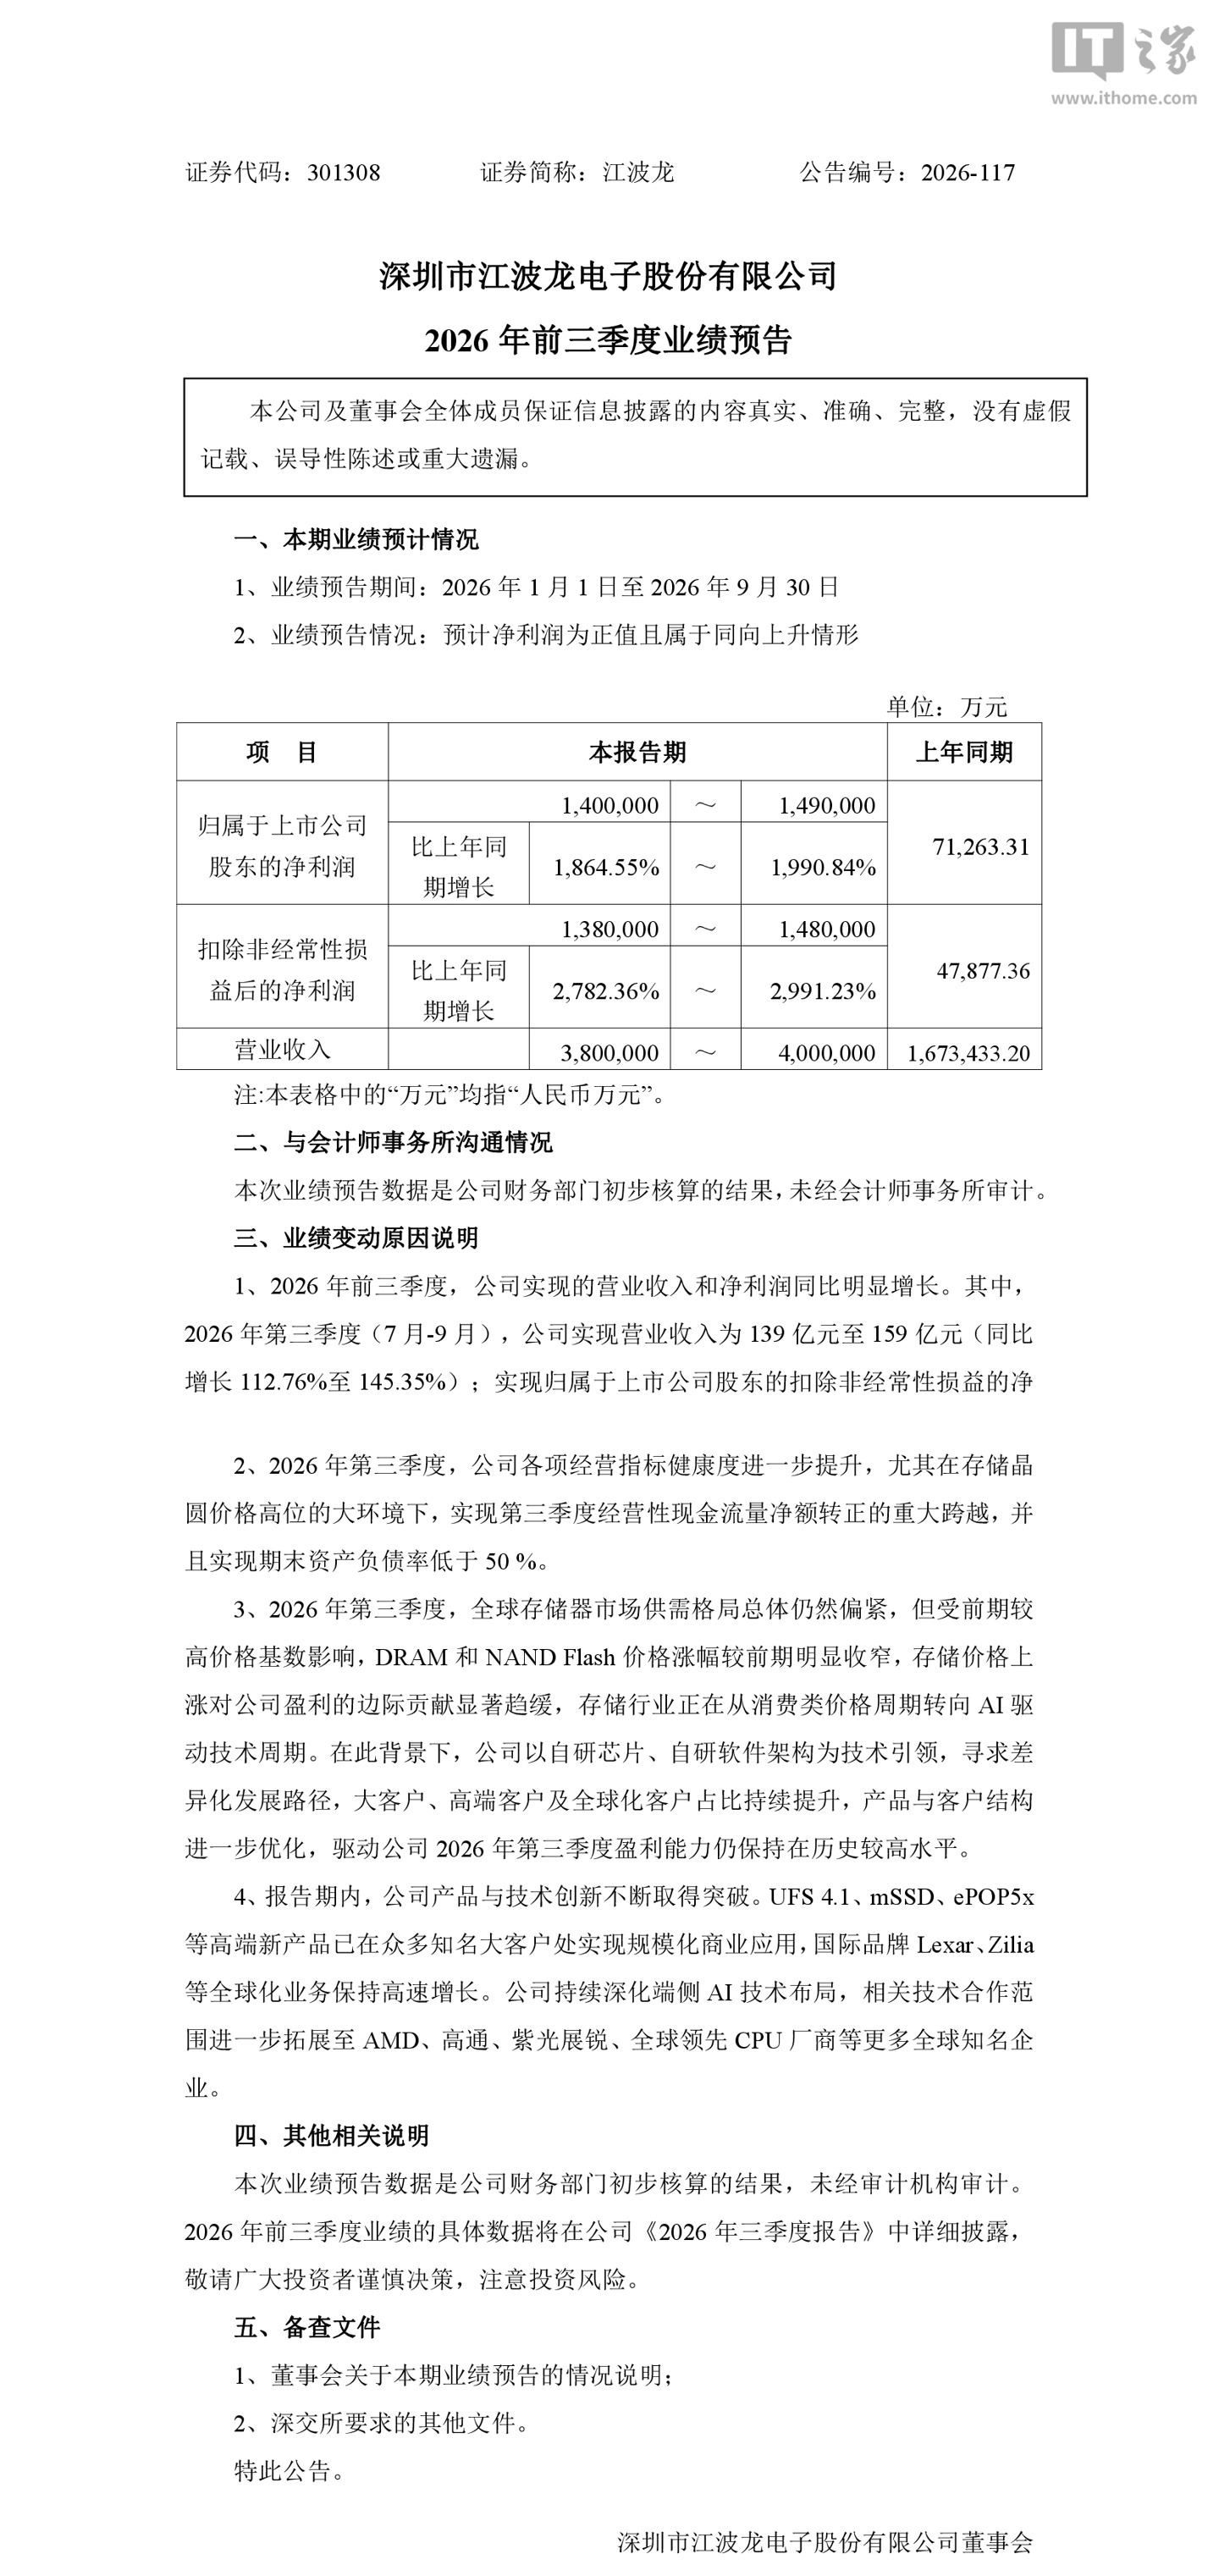
Net profit attributable to the parent company: 14 billion yuan to 14.9 billion yuan, a year-on-year increase of 1864.55% to 1990.84%
Non-recurring net profit: 13.8 billion to 14.8 billion yuan, a year-on-year increase of 2782.36% to 2991.23%
Debt-to-asset ratio: 50%
IT's performance forecast for this time has significantly exceeded the market's consensus expectations, with both net profit attributable to the parent company and revenue growth rates standing out.
Jiangbolong is a domestic enterprise dedicated to the research, development, production, and sales of consumer-grade, industrial-grade, and automotive-grade storage products. Its products cover multiple high-end storage fields such as UFS, SSD, and ePOP.
In the first three quarters of 2026, the company expects to achieve operating revenues of 38 billion to 40 billion yuan, compared to 16.734 billion yuan in the same period last year; it aims to achieve net profits attributable to shareholders of the listed company of 14 billion to 14.9 billion yuan, a year-on-year increase of 1864.55% to 1990.84%, whereas the net profit in the same period last year was 713 million yuan; after deducting non-recurring gains and losses, the net profit is expected to be 13.8 billion to 14.8 billion yuan, a year-on-year increase of 2782.36% to 2991.23%, compared to 479 million yuan for the same period last year.
On a quarterly basis, in the third quarter of 2026, the company achieved operating revenue of 13.9 billion to 15.9 billion yuan, representing a year-on-year increase of 112.76% to 145.35%; net profit after deducting non-recurring gains and losses was 3.753 billion to 4.753 billion yuan, with a year-on-year increase of 740.33% to 964.26%, maintaining a historically high level of profitability.
In the third quarter, the company achieved a net positive operating cash flow, and the asset-liability ratio at the end of the period was below 50%, further indicating an improved level of operational health.
The company stated that the overall supply and demand situation in the global memory market is tight. However, due to the higher price base from earlier periods, the price increases for DRAM and NAND Flash have narrowed significantly compared to before. The marginal contribution of rising memory prices to profits has slowed down, and the industry is transitioning from a consumer-oriented price cycle to a technology-driven cycle driven by AI.
The company stated that it leads with its own-developed chips and software architecture, pursuing a differentiated development path. The proportion of major customers, high-end customers, and global customers continues to increase, and the product and customer structure has been further optimized.
The company stated that with continuous breakthroughs in technological innovation, high-end new products such as UFS, mSSD, and ePOP5x have been commercially adopted on a large scale by well-known customers, and its international business continues to grow at a rapid pace. On the client-side, the technical cooperation with AI has further expanded to include globally renowned companies such as AMD and Qualcomm, opening up additional room for growth.