Key Points
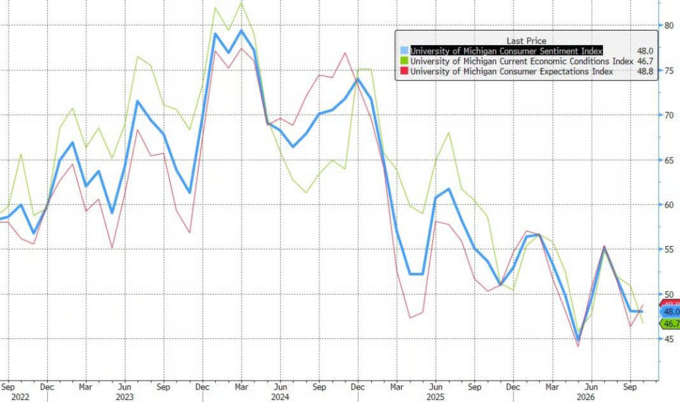
- The final reading of the University of Michigan’s Consumer Confidence Index for October was 48, hitting a five-month low, but it exceeded market expectations.
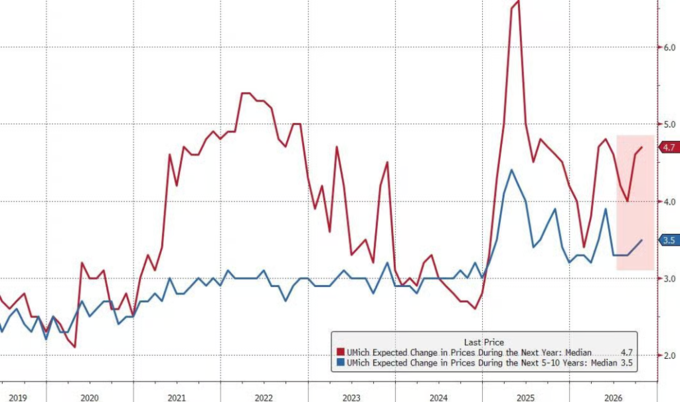
- Consumers' inflation expectations for the next year have risen to 4.7%, and long-term inflation expectations for the next five to ten years have risen to 3.5%, both reaching their highest levels since May of this year, and this is the second consecutive month of increase.
- The S&P 500 Total Return Index has climbed to record highs, while consumer confidence in the United States remains near record lows, resulting in a widening divergence between the two to historic extremes.
U.S. consumer confidence has further weakened under ongoing inflationary pressures, with inflation expectations also rising accordingly. The gap in economic perceptions between Wall Street and the general public has expanded to record levels.
The final reading of the University of Michigan’s Consumer Confidence Index for October was 48, a slight decline from September’s 48.1, reaching a five-month low. Nevertheless, this final value is still higher than the preliminary reading and exceeds the expectations of all economists surveyed by Bloomberg.
Consumers' inflation expectations for the next year have risen from 4.6% last month to 4.7%, and long-term inflation expectations for the next five to ten years have also increased from 3.4% to 3.5%. Both indicators are at their highest levels since May of this year and have seen an upward trend for the second consecutive month.
University of Michigan Survey Director Joanne Hsu stated: "After inflation has been above the target level for five consecutive years, both short-term and long-term inflation expectations have risen in recent months, which poses the risk that inflation expectations may become entrenched."
Meanwhile, the S&P 500 Total Return Index has climbed to record highs, while consumer confidence remains near historic lows, creating a rare divergence between the two.
High prices erode living standards, and cross-party concerns continue to spread
Surveys show that for the fourth consecutive month, an increasing number of consumers are actively mentioning that high prices are dragging down their personal financial situation – this proportion rose to 56% in October, a significant increase from 45% in January of this year.
This trend is prevalent among groups with various political inclinations, with the proportion of Republican voters showing the most significant increase. In contrast, the wealthiest consumer group has not experienced much change in their perception of the burden of high prices since January.
Gasoline prices are one of the important sources of inflation concerns – over 40% of respondents mentioned the issue of oil prices on their own without any prompting, and pump prices have continued to remain above $4 per gallon.
Hsu points out: 'Consumers of all political inclinations unanimously believe that the risk posed by inflation to the economy over the next year is far greater than that of unemployment.'
From a political standpoint, in October, the confidence levels of both Democratic and Republican voters saw a slight rebound, but the confidence of independent voters has been declining for the third consecutive month. Meanwhile, the consumer expectations sub-index recorded an improvement for the first time since July.
Willingness to purchase durable goods drops to a historic low, highlighting interest rate pressures
The current sub-indexes have dropped to their lowest levels in history, with the index for durable goods purchasing conditions plummeting by 18% in a single month to reach its historic lowest point. The main reasons are rising interest rates and increased concerns regarding purchasing power.
Nearly 70% of consumers expect interest rates to continue to rise in the coming year, the highest proportion in over three years.
High mortgage loan rates are further dampening consumers' willingness to purchase homes and engage in large-scale spending. In recent months, the rate of price increases has continuously surpassed the growth of salaries, leading to a steady accumulation of pressure on family budgets. Data released last week also showed that in September, the increase in consumer prices reached a five-month high.
The divide between Wall Street and the general public has reached an historical extreme.
The most notable structural divergence at present may not come from the data itself, but rather from the stark contrast between the market and the public. The S&P 500 Total Return Index has risen to record highs, while the University of Michigan Consumer Confidence Index is near record lows – with the current sub-index falling to a historic low of 44.7.
Consumer confidence has declined by about 10% compared to a year ago, and by about 15% from its peak in February of this year. This divergence reflects two distinctly different economic narratives:
The stock market continues to strengthen driven by corporate earnings growth, the concentration effect of technology stocks, and investors' optimistic sentiment; meanwhile, ordinary families are deeply troubled by high prices, high borrowing costs, and shrinking purchasing power. Historically, such extreme divergences between the stock market and consumer confidence are relatively rare.