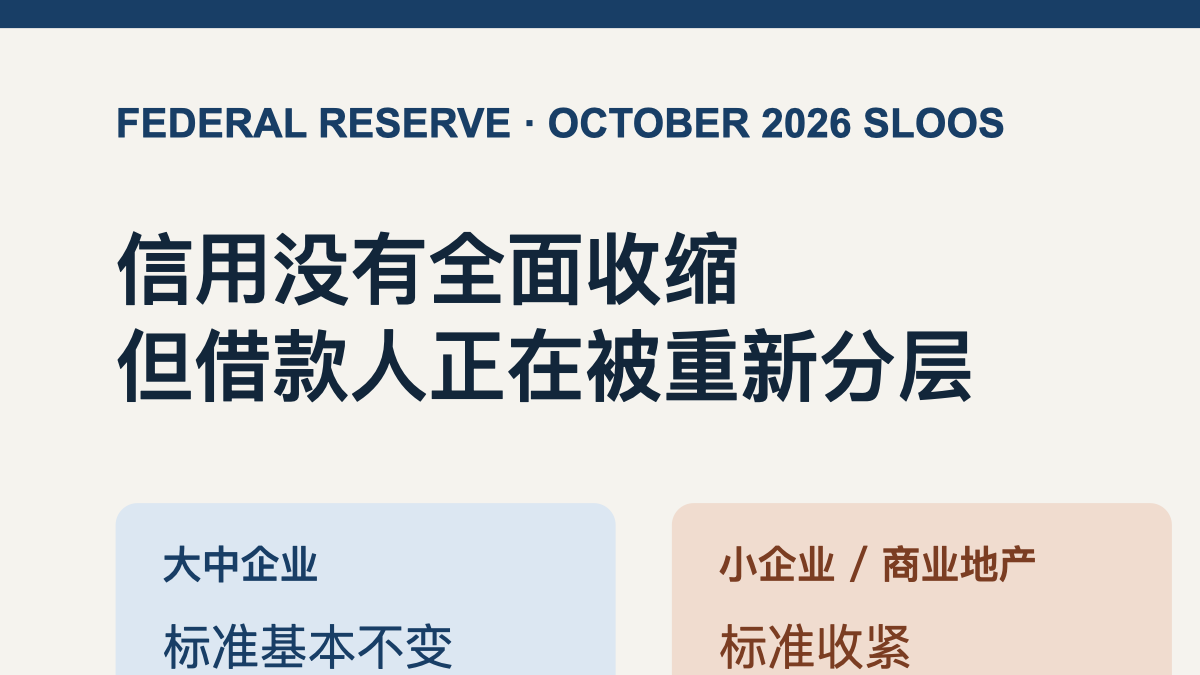
During the same quarter, Bank of America's lending standards for large and medium-sized enterprises remained largely unchanged, but they became more stringent for small businesses; demand for credit cards increased, while demand for auto loans declined; commercial real estate loans faced both tighter standards and reduced demand. The Federal Reserve's October survey of senior credit officers did not conclude with a unified assessment of "credit expansion" or "credit contraction," but rather indicated that funds were being reallocated according to borrowers and purposes.
This survey covered 61 domestic banks in the United States and 18 foreign banks with branches in the U.S. The questionnaire was sent out on September 21st and the deadline was October 5th, mainly reflecting the situation of the third quarter. It does not record the actual loan balances, but rather the banks' assessments of changes in approval criteria, contract terms, and customer needs. Therefore, it serves more as a thermometer for the credit cycle, allowing for an earlier glimpse of the banks' attitudes, although it cannot replace subsequent loan data.
In terms of commercial and industrial loans, banks have maintained relatively unchanged standards for large and medium-sized enterprises with annual sales of over $50 million, but have tightened requirements for small businesses. The premium for higher-risk loans has been increased, and small businesses also face stricter mortgage requirements and lower interest rate ceilings. The most commonly cited reasons by banks are the deterioration of economic prospects or greater uncertainty, as well as problems in specific industries.
The weakest link is not all enterprises, but rather borrowers with less bargaining power.
Large enterprises can switch between bank loans, bonds, and non-bank financing, while small enterprises usually have fewer options. The survey also shows that the loan demand of enterprises of all sizes has weakened overall, due to factors such as reduced investment in equipment, as well as borrowers shifting to more attractive sources of bank or non-bank funding. For small enterprises, a weakened demand does not necessarily mean they no longer need money; it could also be that the prices and terms make borrowing less cost-effective.
The signals for commercial real estate are more consistent. Banks have tightened the standards for loans in three categories: construction and land development, non-agricultural and non-residential properties, and multi-family residences, and demand has also weakened. Commercial real estate projects have long terms and their collateral valuation is sensitive. When interest rates and rental prospects are uncertain, banks tend to raise the barriers first. Even if the benchmark interest rate stops rising, the cash flow pressures during refinancing of existing loans will not disappear immediately.
Lending standards for non-deposit financial institutions have also been generally tightened, covering mortgage credit intermediaries, commercial credit intermediaries, private equity funds, and consumer credit intermediaries, among others. Banks have mentioned not only the economic outlook but also the deterioration of the borrowers' financial strength. At the same time, the demand from commercial credit intermediaries and private equity funds has increased, due to reasons such as working capital needs, investment opportunities, and refinancing requirements. However, a stronger demand does not necessarily mean better terms; sometimes it indicates that alternative funding is more difficult to obtain.
The contradictions on the resident side are reflected in credit cards.
The standards for most types of residential mortgages remain largely unchanged, but subprime mortgages have tightened, leading to a decline in overall mortgage demand. The standards and terms for consumer loans are also generally stable. However, banks have tightened the issuance of credit cards and other consumer loans to borrowers with scores below the required threshold, raised the minimum credit score for auto loans, and reduced credit card limits.
At the same time, demand for credit card loans has increased, while demand for auto loans has decreased. Over the past year, when demand for credit cards was strong, banks often cited consumers adjusting their spending due to changes in the prices of goods and services. Banks are more willing to approve applications from super-high-quality and high-quality customers and less so from subprime customers. In other words, the rising demand for revolving credit among residents has not resulted in an equally relaxed approval process; those with weaker credit quality find it more difficult to obtain credit limits.
This set of results has two implications for economic judgment. First, credit has not been completely frozen; large enterprises, high-quality residents, and some financing channels are still able to obtain funds. Second, the costs and barriers for marginal borrowers continue to rise, and the pressure will first be felt by small businesses, commercial real estate, subprime mortgages, and consumers with low credit scores. The average loan growth rate may remain stable, but this obscures the gradual concentration of internal risks.
Changes in interest rate policy affect the benchmark price of funds, while bank surveys reveal additional factors beyond just prices that influence lending decisions. Even if interest rates fall in the future, mortgage requirements, credit scores, and industry risk preferences may not necessarily relax accordingly. For businesses and households, what truly determines whether they can obtain loans is shifting from "whether there is liquidity in the market" to "who the banks are willing to lend to."
This is also why observing the average loan interest rate is not sufficient. Applications that are rejected do not contribute to the average, and those who voluntarily give up borrowing do not leave a record of their interest rates. SLOOS exposes these thresholds, which are hidden outside of the transaction data, in advance: the turning points in the credit cycle often occur first at the approval stage, and only later are they reflected in the loan balance.