

Polygon added periodic stablecoin payment rules for Open Money Stack on September 21st. Users only need to approve once at the start of subscription, after which merchants can initiate deductions according to the agreed amount, purpose, and validity period. The wallet will verify the conditions at the time of execution, and requests that exceed these limits will be rejected by the contract layer. Users also have the option to revoke their authorization. This design aims to address a long-standing issue with stablecoin payments: users should not be required to reopen their wallets and sign each month for recurring subscriptions.
Traditional bank card subscriptions require merchants to save a payment credential, with automatic deductions upon expiration. The default logic for unmanaged wallets is precisely the opposite: each fund transfer requires the signature of the holder. This is a security advantage for one-time transfers, but it becomes cumbersome for streaming media, software, membership, and cloud services. Polygon OMS attempts to find a compromise between the two by using "restricted permissions" to enable automation without handing over full control of the wallet to the merchant's server.
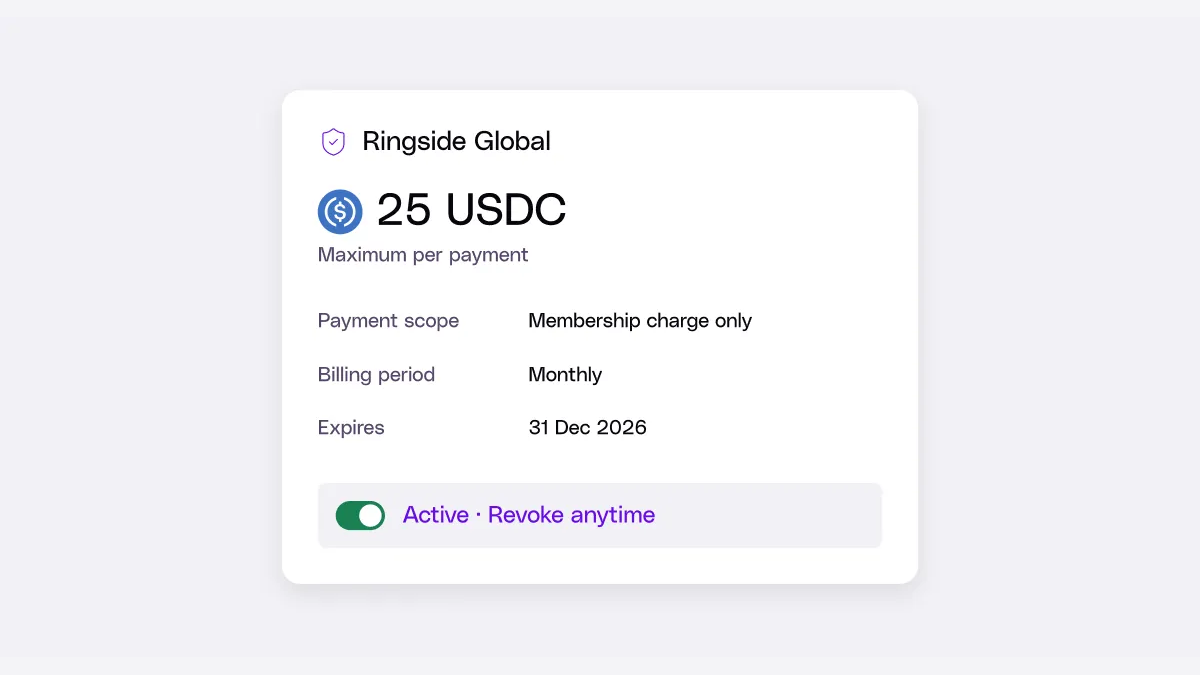
A single authorization is not an unlimited authorization; the amount, scope of calls, and expiration date are all specified in the rules.
According to the mechanism published by Polygon, users first see the price, period, and end date on the product interface before approving a wallet rule. The rule can specify the maximum amount per transaction, the contracts and methods that are allowed to be called, the settlement period, and the expiration time. After the bill becomes due, the merchant's backend sends a request, and the wallet checks each item one by one; payment will only be executed if the request matches the original authorization.
Permissions are stored on the blockchain within the wallet’s Sessions Module. The backend can initiate payments, but it cannot increase the amount or expand the scope of those payments without user approval. This distinction is crucial: if the restrictions were only in the merchant’s database, an attacker could tamper with the rules in the event of a server intrusion or a program error. However, since the restrictions are enforced by the wallet contract, at least unauthorized requests will fail before any assets are transferred.
After a user revokes authorization, subsequent requests will be blocked. This provides a mechanism similar to "cancelling automatic renewal" for stablecoin subscriptions, but the actual experience still depends on whether the application places the revoke button in a prominent location, whether there are fees for on-chain operations, and whether the revoke status is synchronized in a timely manner. Technically, it is possible to revoke, but that does not necessarily mean it is easy to do so in practice. Developers still need to comply with local consumer protection laws and regulations regarding automatic renewal.
Rules cannot prevent all issues either. If a user approves an incorrect amount, misidentifies a merchant, or if there are vulnerabilities in the contract itself, the system will simply faithfully execute the conditions that have been signed. Stablecoin prices, network congestion, insufficient balances, and Gas payments can also lead to failed deductions. Merchants need to implement retry mechanisms, notifications, and grace periods; they cannot simply assume that a failed on-chain transaction means the user has refused to pay.
Stablecoins are moving towards daily payments, and the focus of competition is shifting from "being able to transfer" to "being able to manage relationships."
In the past, on-chain payments emphasized speed and cross-border capabilities, but real business transactions rarely involved just a single transfer. Subscriptions involve package changes, trial periods, refunds, suspensions, taxes, and customer service disputes. This time, what has been added is the underlying authorization and execution capabilities, but it does not automatically resolve all business processes. Enterprises still need to integrate their billing systems, user identities, accounting records, and compliance requirements externally. Polygon
However, implementing periodic payments indeed expands the uses of stablecoin balances. Users can use them to purchase software, content memberships, or regular services, and platforms can integrate payment collection, payment processing, routing, and settlement into the same infrastructure. For cross-border products, stablecoins may reduce the limitations of bank card coverage and local payment acceptance, but the obligations related to fund inflows and outflows, as well as local regulatory and tax requirements, do not disappear as a result.
Compared to credit cards, the advantage of on-chain rules is that the boundaries are more transparent; users can see the approved contracts, amounts, and expiration dates. Merchants also do not need to store card number credentials that can be used for widespread deductions. The trade-off is that users must understand wallet authorization, transactions are more irreversible, and there is no unified framework for dispute resolution by any card organization. The two systems approach problem-solving in different ways, so it is not appropriate to judge their merits solely based on the level of transaction fees.
For development teams, there are four key scenarios that need to be thoroughly tested before going live: whether repeated requests from merchants will result in repeated deductions, whether price increases for packages require re-authorization, how to handle conflicts between authorization revocations and already queued transactions, and whether retries after failures across months will still fall within the original time frame. Improper handling of any of these edge cases could damage users' trust in automatic deductions.
Security audits should also cover the consistency between front-end displays and parameters on the blockchain. It is a typical case of misalignment between the interface and permissions when users see "10 dollars per month" but the signing process allows for a higher limit. Products should present merchants, tokens, amounts, frequencies, and deadlines in language that is understandable to users, and send notifications after each deduction. Transparency should not be limited to block browsers alone.
Polygon describes this feature in the announcement as a new function of OMS, and reminds that the functionality may be restricted or adjusted due to judicial jurisdictions and legal requirements. Therefore, the accurate statement is that "periodic payment rules have been added to the product," which does not mean that all wallets, all countries, and all merchants will be able to use it unconditionally from now on. It represents a step towards the normalization of stablecoins, but whether it can achieve scale depends on whether wallet integration, merchant adoption, and consumer protection keep up in tandem.
As transferring funds becomes increasingly easy, the disparities in payment infrastructure will be reflected in authorization, reversal, reconciliation, and exception handling. Although a single authorization and deduction according to rules may seem like a minor feature, it touches on a key issue regarding the evolution of wallets from personal tools to commercial accounts: how to make automation convenient enough while still keeping control of assets in the hands of users.