

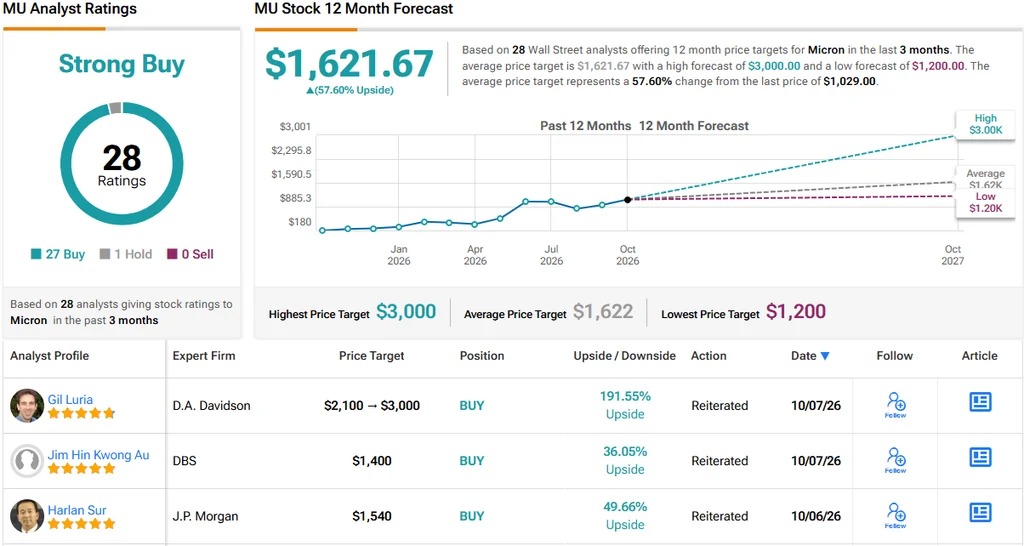
Micron Technology ( Micron , NASDAQ : MU ) seems to have developed a habit of making investors feel nauseous after their financial reports. Following the release of explosive fourth-quarter results for the fiscal year 2024 in late September, the company's stock price has been fluctuating, still 3% lower than before the report was announced. This is not the first time that Micron has faced pressure on its stock price after what should have been very impressive financial reports. After releasing its financial report in June, the stock price tumbled significantly within the following month, with a decline of nearly 30%.
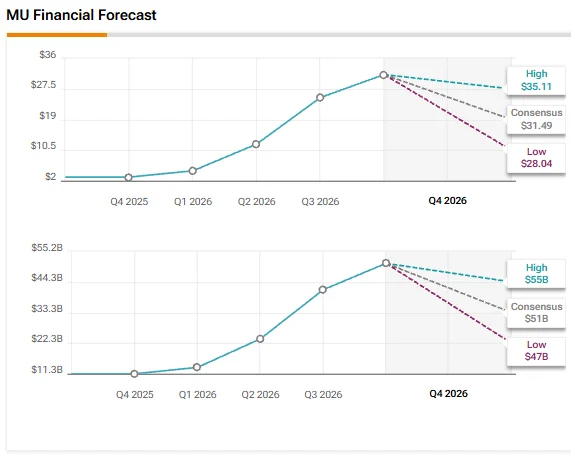
However, before the release of this financial report in September, Micron's stock price had already risen by 273% for the year, so it is not surprising to see some profit-taking. After such a substantial increase, investors had high expectations for the company's performance, leaving little room for results that were not "impressive." And the actual performance was indeed very strong: revenue in the fourth quarter of fiscal year 2024 soared by 379% year-over-year, reaching $54.23 billion, with an adjusted earnings per share of $33.42. The chip manufacturer also expects sales in the current quarter to reach $61.5 billion, indicating that the demand for storage driven by AI continues to be strong.
However, a top investor using the pseudonym Juxtaposed Ideas believes that the recent stock price performance actually presents an opportunity worth considering. According to the TipRanks rankings, he is among the top 2% of stock experts. He argues that short-term price fluctuations should not overshadow Micron's longer-term prospects.
Juxtaposed Ideas explained, "I believe the best time to buy is during the most pessimistic moments (quoted from Sir John Templeton), and the current ongoing weakness in momentum has prompted me to raise my buying rating."
His optimistic judgment is partly based on the changes that are taking place in the storage chip industry. Historically, this industry has always experienced painful cycles of oversupply and falling prices. However, AI may bring higher stability than previous stages of technological growth, especially as cloud service providers continue to make substantial investments in computing infrastructure.
Mitsubishi Electric's 26 strategic customer agreements are particularly important in this regard, as these agreements extend the contract period until 2031, which helps to increase the visibility of future revenue. On the other hand, the chip manufacturer disclosed that its remaining obligations amount to $150 billion. These contracts include financial commitments and pricing arrangements that may make future revenue more predictable, while also reducing exposure to downturns in traditional industries.
Meanwhile, cloud computing giants continue to make substantial investments in AI infrastructure, thereby supporting the demand for advanced storage products. Micron expects that the supply-demand situation will remain tight until 2027 and 2028, which may continue to support favorable pricing and profitability.
Juxtaposed Ideas believes that opportunities are not limited to data centers; the fields of robotics and autonomous vehicles also deserve attention. As AI becomes more deeply integrated into physical machines, these applications may create additional sources of chip consumption.
Valuation is another reason for his bullish outlook. Micron's current forward enterprise value/sales ratio is 4.05 times. Compared to several competitors in the storage and storage device industry, this valuation is quite attractive, especially considering the chip manufacturer's continuously strengthening cash generation capability and healthier balance sheet.
This investor summarized, "Therefore, although MU may lag in mid-term stock price performance, I believe that this presents a great buying opportunity for patient investors."
Disclaimer and Disclosure Report an issue
Micron Technology News MORE