

A significant portion of the concerns surrounding Micron Technology stem from China's ChangXin Memory ( ChangXin Memory Technologies ). The company recently released a new DRAM unit design that may allow manufacturers to integrate significantly more memory onto silicon chips.
This development has sparked concerns in the market about intensified competition and potential future oversupply, while the broader weakness in the semiconductor sector has also increased selling pressure.
However, investor Joseph Montezuma believes that the market may have overreacted. He stated that Micron's recent pullback makes this stock more attractive compared to a week ago.
His confidence stems from his judgment of how much pessimistic expectations have already been factored into the valuation of Micron.
Montezuma explained, "Compared to a week ago, one thing I can now accept better is that even though we encountered an downward cycle earlier, the stock price has already reflected that."
One reason for the bullish outlook is that Micron has been working hard in recent years to reduce its vulnerability to the well-known sharp cyclical fluctuations in the storage industry. The chip manufacturer has signed 26 strategic customer agreements, which are expected to contribute more than 35% of its revenue by 2030. These contracts also include protection clauses designed to mitigate financial impacts during times of weakened demand.
At the same time, Micron demonstrates discipline in controlling production, prioritizing the needs of data center customers who offer higher profits and avoiding unnecessary capacity expansion. The company's recently approved $35.16 billion stock repurchase plan may also provide additional support starting from December 9th, although the company is not obligated to repurchase any specific number of shares.
In addition, there are valuation factors to consider. Montezuma believes that although stock prices may continue to fluctuate in the future, the current valuation provides an attractive entry point for investors. His baseline valuation is $1,250 per share, which suggests a potential upside of about 40% from the current level; a more optimistic scenario would see a price of $1,760 per share. Even in his pessimistic valuation of $820 per share, this is based on the assumption of a nearly 70% drop in storage prices, indicating that he has taken into account a considerable amount of pessimism in his calculations.
However, Montezuma also acknowledges that there may still be more fluctuations ahead, especially if competition from China accelerates or if new manufacturing capacity is deployed earlier than expected. He is also concerned that cloud computing giants may eventually reduce their spending, thereby weakening the demand for high-priced memory products.
Nevertheless, he seems willing to tolerate further declines, waiting for his investment logic to pay off.
Montezuma summarized, 'Another piece of news from Shanghai, or a slowdown in price increases during a certain quarter, could potentially impact this stock again, but I can accept that.'
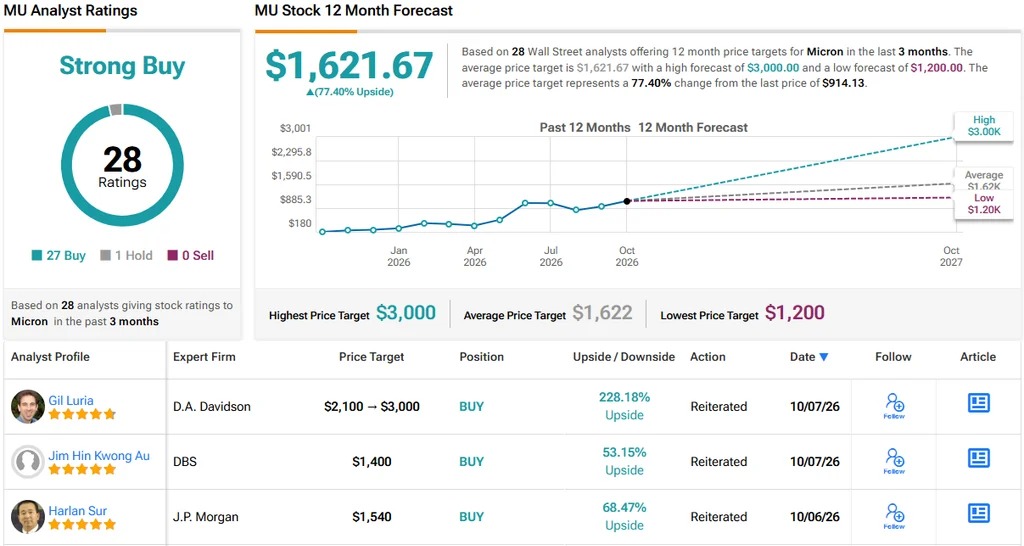
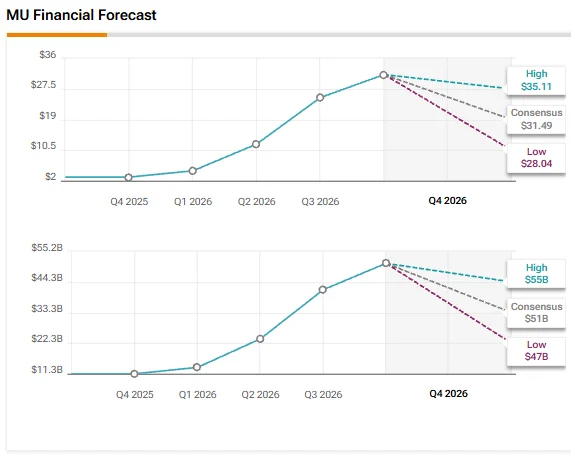
Wall Street seems to be more optimistic about Micron's prospects. The market's 12-month average target price is $1,621.67, which represents a potential increase of about 77% compared to the closing price on Wednesday. The stock currently also has a unanimous rating of "strong buy," backed by 27 "buy" ratings and only 1 "hold" rating.