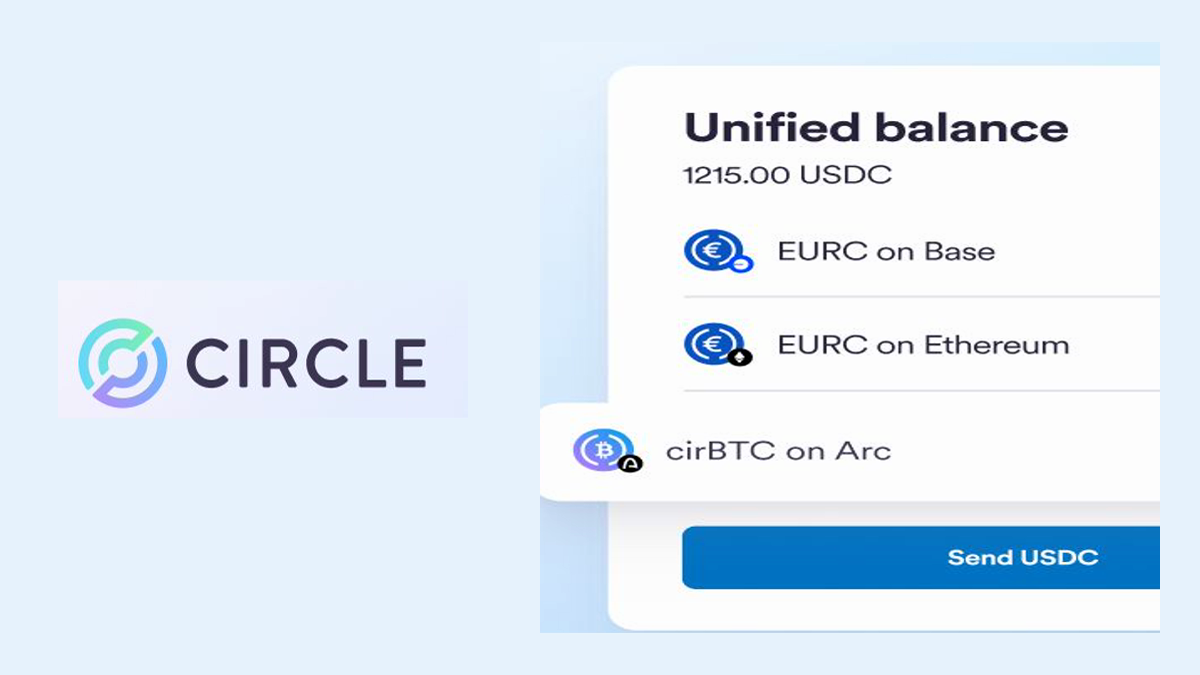


A company that engages in cross-chain payments often doesn't lack assets; rather, the assets are on the wrong chains. For example, Chain A has euro-stablecoins, while Chain B requires settlements. As a result, the operations team has to maintain inventory on multiple networks. On October 23rd, Circle announced that Circle Gateway would start supporting its Bitcoin product cirBTC and the euro-stablecoin EURC in addition to USDC, allowing developers to manage unified balances across supported chains separately according to their assets. This change occurred at the asset integration layer of Gateway. It cannot be said that assets on all chains now have the same liquidity, nor can it be claimed that cross-chain transactions no longer involve settlement or counterparty risks.
The official use cases include payments, withdrawals, transaction orders, and high-frequency applications: after funds are deposited and finally confirmed, applications can call upon the balance of the corresponding assets on the supported chains, without the need to maintain an equal amount of liquidity on each chain separately. For wallets and payment service providers, the value lies in more flexible inventory management; for ordinary users, the experience may be closer to "one balance for the same asset." However, assets still need to be distinguished by currency. cirBTC, EURC, and USDC cannot be considered as interchangeable cash just because the interfaces are unified.
One asset, one balance; the supported range still has clear boundaries.
The scope of disclosure for Circle is as follows: cirBTC receives support from Gateway on Arc and Ethereum; EURC covers Arc, Avalanche, Base, Ethereum, Solana, and World Chain. This list indicates the supported networks for this product and does not imply that all networks have the same level of liquidity. It cannot be extrapolated to networks that are not listed. If developers provide services on other chains, they still need to assess additional bridging, exchange, or traditional fund transfers. The premise for a unified balance is always that the funds have entered the supported systems and the corresponding confirmations have been completed.
cirBTC represents an encapsulated asset that corresponds to a Bitcoin position, while EURC is a stablecoin denominated in euros. The financial roles undertaken by the two are completely different. Holders of the former need to be aware of the risks associated with Bitcoin custody, reserves, redemption, and on-chain contracts; users of the latter also have to consider the exchange rate between euros and their own accounting currency. Gateway reduces operational friction in multi-chain inventory management without altering the price of the underlying assets, their reserve structure, or legal compliance requirements. If a company displays both types of assets on the same console, its balance sheet must still account for them separately.
Circle indicates that the existing integration and behavior of USDC remain unchanged. New assets can utilize the same set of Gateway contracts, API, and development tools. For teams that have already integrated with USDC, this represents a starting point for expanding functionality, rather than automatically obtaining production capabilities for all cryptocurrencies with one click. If an application needs to add cirBTC or EURC, it still needs to handle issues related to precision, limits, risk control rules, on-chain transaction fees, user authorization, and abnormal states. Before the wallet displays a concise number, the backend needs to know which deposits have been finally confirmed, which withdrawals are pending completion, and how to refund or retry in case of cross-chain request failures.
This announcement also highlights "quick cross-chain access after final confirmation of the deposit" as a selling point. Readers should pay attention to the timing starting point: since blockchain confirmation itself takes time, the subsequent access speed of a few hundred milliseconds does not represent the total time required from the funds being credited to the bank account to the funds being available for receipt on the chain. Different network congestion levels, transfer methods, and compliance checks can affect the entire process. If companies want to promise customers about payment timeliness, they should record the median and tail delays of the end-to-end process, rather than referring only to a certain internal processing time.
For payment institutions, what truly needs to be verified is the capital turnover.
In the past, a common cost associated with multi-chain operations was "reserving inventory for the worst-case scenario": a portion of funds was kept on each chain to ensure that payments could be made in case of sudden orders. If the system was stable, organizations could reduce the idle assets across different chains and use the same pool of funds for more transaction routes. However, this approach's effectiveness needed to be proven by actual fund utilization rates, failure rates, and reconciliation costs. Especially during large, frequent withdrawals, it was more critical to see if the system could handle requests in multiple directions simultaneously than to simply demonstrate a small cross-chain transaction.
The fees also need to be verified according to the asset and network. The product information for Circle mentions that there are discounts on the costs of new assets Gateway on Arc when they are launched, while other networks have their own standards; such phased arrangements can change and should not be considered permanently free. The total cost incurred by users may also include on-chain transaction fees, exchange price differences, custody, and operational expenses. If new liquidity or asset risks are introduced in pursuit of lower fees on one route, the savings on paper may not necessarily benefit the end-users. Operators should review each item carefully in the formal contract and on the latest fee pages.
Compared to traditional bridging, the core improvement proposed by Gateway is to allow applications to access supported assets on-demand from a unified balance; however, it does not eliminate the possibility of systemic failures in cross-chain financial activities. Contract risks, key management, the finality of chains, the availability of gateway services, and redemption arrangements are still areas that require separate scrutiny. What developers should practice most is not just the successful scenarios, but rather how to determine asset status, prevent double payments, and explain the reasons for delays to users in cases such as chain suspensions, withdrawal delays, quote expirations, and asset freezes.
Circle describes this expansion as a step towards using its cross-chain infrastructure for multiple assets rather than just a single US dollar asset. This claim is supported by specific products: cirBTC and EURC have indeed been added to Gateway's supported list. However, the ability to call upon "more assets" is far from meaning that "cross-chain payments have solved all problems." What is worth paying attention to in the next phase is whether the actual business volume, service stability, the range of supported chains, and the cost of asset usage can continue to be disclosed. For institutions, a balance interface is just the beginning; only auditable cash flows are proof of a product's maturity.