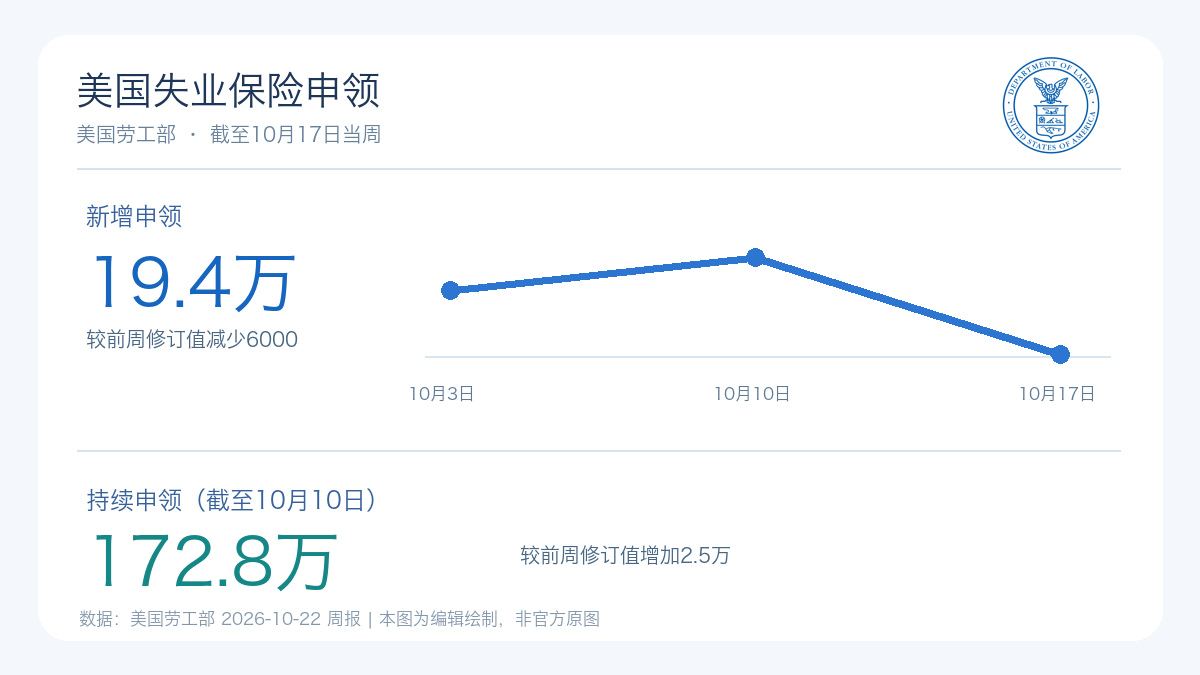


The U.S. Department of Labor released its weekly unemployment insurance report on October 22, which presented a set of figures with contrasting trends: As of the week ending October 17, the number of first-time unemployment claims, after seasonal adjustment, was 194,000, which is 6,000 less than the revised figure of 200,000 from the previous week; the four-week moving average was 197,750, a decrease of 1,000 from the previous week. However, as of the week ending October 10, the number of people receiving unemployment benefits continuously was 1.728 million, an increase of 25,000 from the revised previous figure. Although the weeks covered by these two indicators are not the same, they serve to remind the market that a smaller increase in new unemployment cases does not mean that those who have already lost their jobs will be able to find new jobs quickly.
Initial claims are typically used to observe short-term changes in corporate layoffs, as they count the number of new applicants who enter the unemployment insurance system; continuing claims reflect the number of people who are still receiving benefits, and are influenced by factors such as the speed of re-employment, eligibility rules, and administrative processing. These two figures should not be simply added together, nor can they be directly equated with the total unemployed population in the United States. For macroeconomic readers, what is truly important is not whether a certain figure reaches a low point for a few weeks, but rather why there is a divergence between initial claims and continuing claims in the same announcement.
What's the point of explaining when it can't really explain anything in the end?
The Department of Labor revised the figure from 199,000 at the beginning of the previous week to 200,000, so the decrease of 6,000 this time is calculated based on the revised value. Over four weeks, it is possible to smooth out the fluctuations in a single week caused by holidays, weather, and varying processing speeds in different states. The current figure is 197,750. Compared to the 194,000 in a single week, the average change is small, indicating that the recent increase in new claims is generally within a lower range, rather than a sudden wave of large-scale layoffs.
The unadjusted initial claims were 172,390, which is 19,321 less than the previous week. These figures are not two contradictory sets of "actual unemployment numbers"; rather, they represent the same type of claims processed differently in statistical methods. Seasonal adjustment attempts to remove the seasonal variations that occur each year, making comparisons between different weeks more meaningful; the unadjusted figures, on the other hand, retain the actual number of claims filed for that week. If the reporting does not clarify the methodology, it is easy to mistakenly assume that one set of figures is incorrect.
There are also inherent omissions in initial job applications. People who have not applied or do not meet the qualifications for unemployment insurance are not directly included in this statistic, nor can those who have already left the labor market be identified through it. Companies may reduce recruitment without laying off employees immediately, and changes in the number of contract workers and self-employed individuals may not be reflected promptly in state unemployment insurance claims. Therefore, a low initial number of job applications is more indicative of "no significant increase in new layoffs among insured employees" rather than "a strong employment market overall." To evaluate job opportunities, it is also necessary to look at subsequent data such as new jobs created, unemployment rates, recruitment, and labor participation.
Special caution is needed when dealing with the state-specific figures. The report lists changes in each state under different reference weeks and seasonal adjustment conditions. Local weather, administrative backlogs, and arrangements by large enterprises can all cause short-term fluctuations. It is not appropriate to declare that a state's economy has entered a recession just because the number of claims in that state has increased in a particular week; nor should we ignore the difficulties faced by certain local industries just because the national figures have decreased. The greatest advantage of weekly data is its timeliness, but its greatest disadvantage is also the higher level of noise (uncertainty).
Continuing to seek employment upwards means that the issue of re-employment deserves close attention.
As of the week of October 10th, the number of continued claims increased by 25,000 to 1.728 million, with a four-week average increase of 4,000 to 1.711 million. The Department of Labor also announced that the insured unemployment rate was 1.1%, which is the same as last week's unadjusted figure. The continued claims data refer to those who are still receiving benefits, not all job seekers; moreover, the reference week for these claims lags behind the initial claims by one week. Due to these different measurement methods, it should not be interpreted as "another 25,000 unemployed people added this week," but rather as a continuation of an increase in the number of people receiving benefits compared to earlier periods.
There are more than one possible explanations: more new applicants have not yet found jobs, the time for some to receive benefits has been extended, or there have been revisions to administrative data. It will take more weeks of data to distinguish between these possibilities. If initial job applications remain low and renewals continue to rise, the market will pay more attention to the situation where "firms are not laying off many employees, but recruitment and re-employment are slow." If renewals fall back quickly, this week's increase may just be a short-term anomaly. It is not sufficient to use a single weekly report to determine a turning point in employment.
Financial markets often directly link low initial job applications to interest rate expectations, with the logic being that if labor demand remains strong, the necessity for policy easing may decrease. However, central bank policies depend on inflation, employment, and the overall economy, and weekly job applications represent only a small portion of this picture. Especially since this increase in renewals of applications is upward, it is even more necessary to cross-check with the next round of monthly employment surveys. To interpret "no surge in layoffs" as "employment has fully accelerated" is beyond what the data can support.
The most reliable way to interpret this weekly report is that as of October 17th, there was a decrease in new unemployment claims, and the four-week average was also slightly lower; however, the number of people continuing to claim benefits from the previous week increased. The job market has not yet shown signs of a widespread surge in layoffs, but whether the rate of re-employment can improve remains unanswered by this report. In the next step, it will be more valuable to pay attention to the trend over several consecutive weeks, revisions to previous figures, as well as monthly employment and unemployment data, rather than drawing conclusions based on the single figure of 194,000.
From the perspective of corporate decision-making, it is also necessary to keep records of layoffs and recruitment separately. A company that does not lay off employees may have stable orders, or it may simply be unwilling to bear the costs of rehiring and training in the short term; on the other hand, when a company stops creating new positions, it may make it seem to job seekers that there are fewer opportunities available, but this will not immediately lead to an increase in initial job applications. These two scenarios have different implications for wage growth, consumption, and policy. The rise in rehiring rates mentioned in the report reminds us that only by observing both the speed at which workers enter the unemployment insurance system and the speed at which they leave it can we get a more complete picture of the job market.
The report also includes a revision mechanism: state-level data will be adjusted according to subsequent reports and seasonal factors. The figure of 200,000 from the previous week is already an updated value. Therefore, when the next report is released, it is necessary to first verify whether the figure of 194,000 for this week has been revised before comparing the changes in the new week. Treating an initial value as an unchangeable fact can easily lead to an exaggeration of the differences between adjacent weeks. For readers who do not engage in frequent transactions, the average trend over several consecutive weeks is more reliable than the single figure that appears on the screen on any given day.