CBN News, November 15, 2026, 10:02:25 - Listen to the news
Author: Fan Zhijing Editor-in-Chief: Pan Yinru
This week, the international market has seen rapid changes, and the resignation announcement by NVIDIA CEO Jensen Huang has drawn widespread attention.
In terms of the market, U.S. stocks were generally on the rise, with the Dow Jones Industrial Average increasing by 2.07% for the week, the Nasdaq Composite Index rising by 3.53%, and the S&P 500 Index gaining 2.51%. European stocks also performed well, with the UK FTSE 100 Index up by 2.18%, Germany's DAX DAX Index rising by 3.73%, and France's CAC CAC 40 Index increasing by 3.01%.
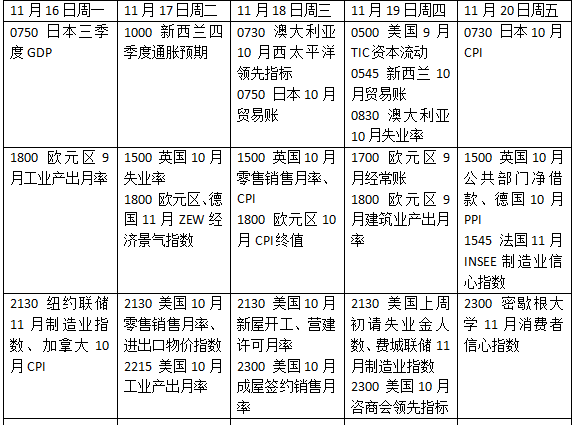
There are quite a few highlights next week. The minutes of the Federal Reserve's October meeting will be one of the core focuses of market attention, as investors will look for clues regarding the timing and extent of future interest rate hikes. British economic data will also be closely monitored, as it will be used to assess whether the market's high expectations for interest rate hikes by the Bank of England are reasonable. NVIDIA will release its first financial report since the departure of Jensen Huang, while the much-anticipated IPO from the emerging artificial intelligence company Anthropic will make its debut.
According to Xinhua News Agency, the 33rd APEC ( APEC ) Leaders' Informal Meeting will be held in Shenzhen, China from November 18th to 19th. This is the first time in 12 years that China has served as the host of the APEC again.
The Federal Reserve releases meeting minutes
The Federal Reserve will release the minutes of its October meeting next Wednesday (the 18th). Although September's inflation data indicated an acceleration in inflation, the Fed still kept interest rates unchanged at that meeting.
Since that meeting, expectations for interest rate hikes have risen due to strong employment data in October, inflation higher than expected, and hints from Federal Reserve Governor Christopher Waller that a 50-basis-point hike could occur in December. Data from the London Stock Exchange Group ( LSEG ) shows that the market currently prices a 25-basis-point hike in December at 89% probability, and a 50-basis-point hike at 11% probability. Analysts at Tinda Economics ( Investec Economics ) stated in a report: "The question is whether the Federal Reserve regrets keeping interest rates unchanged at last month's meeting and hopes to 'make up for it' by raising them later."
Several Federal Reserve officials will deliver public speeches, among whom Federal Reserve Chairman Kevin Warsh will speak at the Federal Reserve's Productivity and Employment Working Group meeting on Monday (the 16th).
In terms of economic data, indicators such as October's retail sales figures, new home starts and completed homes for sale, the weekly initial unemployment claims, the November Federal Reserve Manufacturing Index, the Philadelphia Fed Business Outlook Survey, and the final reading of the University of Michigan Consumer Confidence Index are worth paying attention to.
As the financial reporting season enters its final sprint, NVIDIA's financial reports may receive even more attention now that Jensen Huang has left the company. Retail business results will begin to be disclosed, with companies such as Home Depot, Lowe's, Target, and Walmart releasing their financial statements, and Disney's financial report will also attract external attention.
The long-awaited debut of the artificial intelligence laboratory Anthropic in the public market is scheduled for next week, and it could become a catalyst for sentiment surrounding artificial intelligence. Documents from the U.S. Securities and Exchange Commission show that Anthropic plans to sell 825 million shares at a price range of $70 to $78 per share in its initial public offering. At the upper end of this pricing range, the offering is expected to raise $64.4 billion.
Crude Oil and Gold
Affected by the changes in the Middle East situation, international oil prices have become more volatile. The near-month contract of Brent crude oil for January delivery closed at $95.84 per barrel, a weekly decline of 2.5%; West Texas Intermediate (WTI) crude oil for December delivery ($WTI) was reported at $88.56 per barrel, also with a weekly decline of 2.5%.
On the 12th, U.S. President Donald Trump stated that Washington no longer needed to reach an agreement with Iran, which raised doubts about the prospects for negotiations in the market. The Netherlands International Group ( ING ) believes that the recovery of production in the Middle East has alleviated concerns about immediate supply, but the reliance on alternative export routes still makes transportation vulnerable to disruptions. The speed at which traffic through the Strait of Hormuz returns to normal remains a key factor affecting oil prices.
The International Energy Agency stated on the 13th that as exports from the Middle East are recovering at a faster pace than demand growth, the global oil market is expected to return to a state of oversupply in the fourth quarter, marking the first time such an oversupply has occurred since the outbreak of conflicts in the region. In October, global oil supply increased by 2.3 million barrels per day to 105.4 million barrels per day. As a result, the agency raised its forecast for supply in the fourth quarter by 3.3 million barrels per day. Gulf oil exports, excluding those from Oman, reached 18.4 million barrels per day, still about 26% lower than pre-war levels.
The precious metals market has seen its largest decline since June. The nearest-month contract of COMEX gold for November delivery fell by $184.80 this week, a decrease of 4.55%, closing at $3,879.70 per ounce; the nearest-month contract of COMEX silver fell by $2.7720 this week, a decrease of 5.35%, closing at $49.031 per ounce.
Spot gold hit its lowest level since October 2025 on Thursday, as rising oil prices and fading hopes for peace in the Middle East sparked concerns about increased inflation and rising interest rates. Federal Reserve Vice Chair John Williams indicated that further interest rate hikes could be possible as the central bank seeks to reduce high inflation levels in a healthy economy. Independent analyst Tai Wong said, "This has been a tough week for gold; with strong support from the Fed's hawks, it may be difficult for gold to regain the $4,000 level."
Although gold is generally regarded as a hedge against inflation, higher interest rates increase the opportunity cost of holding unyielding gold bars, reducing its attractiveness to investors. "Short-term momentum indicators have already reached extreme oversold levels during the session," said Wang Xiao, a senior market analyst at OANDA. "A possible short-term factor that could be bullish for gold would be a sudden shift in U.S. Treasury yields, which could drag down the dollar."
UK economy boosts expectations for interest rate hikes
Data released this week show that in the eurozone, GDP grew by 0.4% quarter-on-quarter and 1.3% year-on-year in the third quarter. Both figures are in full line with market expectations, indicating that the economy as a whole continues to expand moderately. Employment in the third quarter saw no quarter-on-quarter growth, far below the market's forecast of a 0.2% increase. The annual employment growth rate slowed from 0.5% to 0.4%, indicating a clear slowdown in the expansion of the labor market. Markets have raised their expectations for the European Central Bank's cumulative interest rate hikes by the end of 2027 from 52 basis points at the beginning of this week to 72 basis points.
The economic calendar for the eurozone in the coming week is relatively light. Data on industrial production in the eurozone for September, the final inflation figures for October, Germany's ZEW economic sentiment index for November, and the preliminary consumer confidence index for the eurozone in November are worth paying attention to.
In the third quarter of the UK, GDP grew by 0.7% on a quarterly basis and by 1.9% year-on-year, marking the highest single-quarter growth rate since the first quarter of 2024; in September alone, GDP grew by 0.2% on a quarterly basis, which was better than the market's previous expectation of zero growth. The service sector as a whole grew by 0.9%, with computer programming and AI related digital services being the key drivers of growth. AI related expenditures directly contributed to an increase of 0.3 to 0.4 percentage points in GDP; in September, manufacturing output grew at a monthly rate of 0.7% and at an annual rate of 4.4%, both significantly higher than market expectations.
After the data was released, the market probability of the Bank of England raising interest rates by 25 basis points in December increased to 73%. Swap contracts indicated that the cumulative interest rate hike by the end of 2027 had risen from 70 basis points at the beginning of this week to 93 basis points, and the yield on 10-year UK government bonds increased by 18 basis points in a single week.
The UK will see a dense release of data over the coming week. Market attention will be focused on employment and inflation figures, which may provide clues as to the pace of interest rate hikes by the Bank of England. Other indicators worth watching include public sector financial data for October. This will be the first release of public finance data since Chancellor of the Exchequer John Hilley announced a relatively modest budget in October. UK retail sales data is also crucial, as it may indicate whether high energy costs are affecting consumer spending.
Next Week's Highlights
- US Stock Gold | NVIDIA Brings the AI Sector into a Period of Uncertainty, How Will Three Major Risk Events Next Week Affect US Stocks?
- Anthropic IPO has become one of the focal points.
- AI Evolution Express | Anthropic Releases New Fable and Mythos Models
- NVIDIA releases the GR00T 2 world action model; IBM and Microsoft launch a brand-new AI intelligent agent platform.
- Next Week's Overseas Market Highlights | What Signals Will the US CPI in October Send? How Will Geopolitical Factors Disturb Global Markets?
- Has the market already absorbed the impact of the Democratic Party's overwhelming victory in the U.S. mid-term elections on the Middle East situation, oil prices, and the tech sector? Could geopolitical events such as the Russia-U.S.-Ukraine talks disrupt risk appetite?
- First interest rate hike in three years! Bank of England: This won't be the last time
- Traders increased their bets on further interest rate hikes, leading to a sell-off of British government bonds.
- Gold at $3,900 forces institutions to "surrender," while retail investors remain bullish
- Midterm elections and non-farm payroll data could trigger a huge shock in the market.