

Alibaba's stock price rose 4.5% during trading on Friday, following a move by Bank of America analyst Joyce Ju who raised his target price from $175 to $178 while maintaining a "buy" rating. The new target price represents approximately 68% upside from Thursday's closing price of $105.70. Ju stated that Alibaba's current valuation does not fully reflect the expected improvement in earnings, describing this as an opportunity where "the earnings turnaround has not been fully priced in."
Bank of America raised its profit forecast by 3% to 9%. The bank stated that Alibaba's current trading price is equivalent to 15 times the estimated non-GAAP profits for the fiscal year 2027 and 11 times the profits for the fiscal year 2028, indicating that its valuation has not yet reflected the expected growth.
Cloud business growth may boost Alibaba's profits.
Bank of America expects Alibaba's revenue for the September quarter to grow by 10% year-on-year, with an adjusted EBITA of 30 billion yuan. This will be higher than the market consensus forecast of 26 billion yuan and also higher than the 27 billion yuan in the June quarter.
It is expected that cloud business revenue will grow by 52%, higher than the 45% in the previous quarter. External customer demand may increase by nearly 55%, and the profit margin of cloud business is expected to reach 12.9%, up from the previous 11.6%. Improved training efficiency should also help reduce the losses of the AI laboratory and application business from 14 billion yuan to 11 billion yuan.
Bank of America expects that starting from the December quarter, cloud business profits will be able to cover the losses of the AI business. This could help the merged cloud and AI business to shift from a loss of over 20 billion yuan in fiscal year 2026 to achieving break-even in the second half of fiscal year 2027. The bank forecasts that the cloud business will grow by 52% in fiscal year 2027, 57% in fiscal year 2028, and 41% in fiscal year 2029.
E-commerce businesses are facing pressure on consumer spending
Bank of America expects that due to weak consumer spending in China, Alibaba's customer management revenue ( CMR ) for the September quarter will decline by 5% year-on-year.
Despite this pressure, the company still expects its EBITA to grow by 2% after adjustments to its e-commerce business. Excluding instant zero-after-sales services, China's e-commerce business EBITA is expected to remain roughly flat. The loss in the instant retail business is expected to narrow from 9.8 billion yuan in the June quarter to 9.6 billion yuan.
Is it worth buying Alibaba stock now?
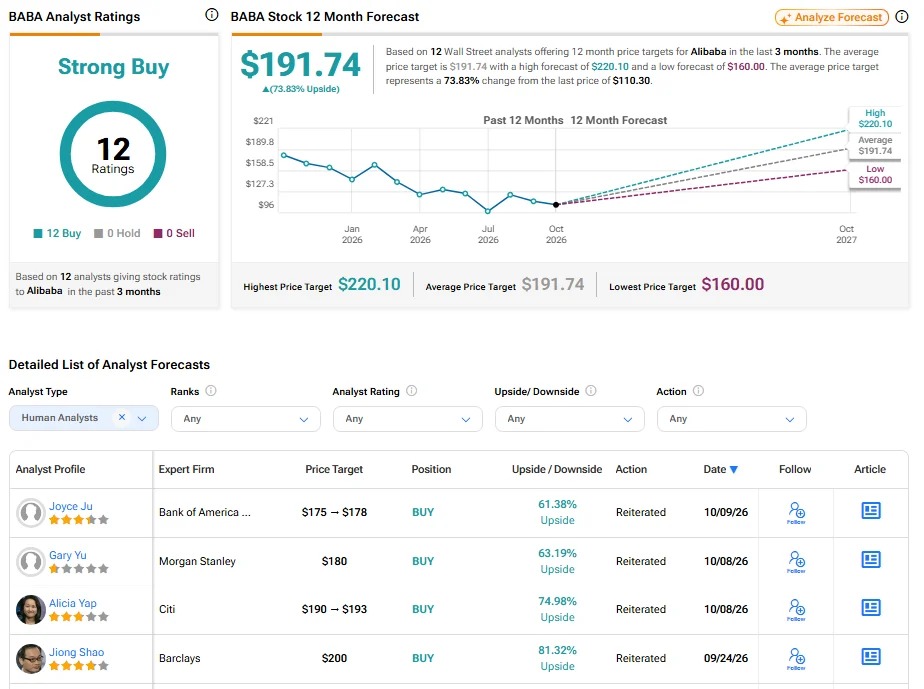
Wall Street as a whole still holds a constructive view on this stock. Based on 12 'buy' ratings over the past three months, Alibaba currently has a unanimous rating of 'strong buy'. The average target price for BABA is $191.74, which indicates a potential upside of 73.83% from the current level.
Author: TipRanks