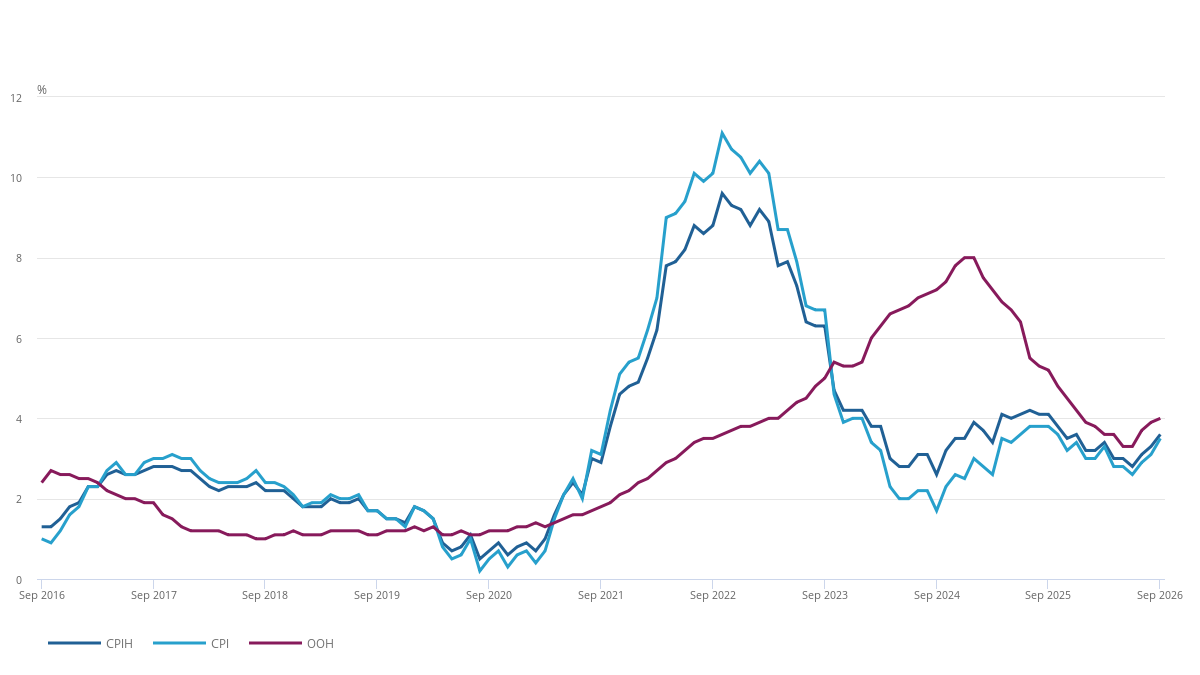


UK inflation rose again in September. On October 21, the Office for National Statistics (ONS) announced that the Consumer Price Index (CPI) CPI rose by 3.5% year-on-year, higher than 3.1% in August; the Cost of Living Index, which includes the cost of owning a home, CPIH rose by 3.6% year-on-year, up from 3.3% the previous month. Both figures have increased, but they represent different indicators, so the increase in CPIH cannot be directly equated with the more familiar CPI increase in the market. For households, the real issue behind these numbers is how the rise in fuel, transportation, and service prices will affect their daily expenses; for the market, the question is whether this upward trend is a short-term fluctuation or a more persistent pressure.
Looking at the changes on a monthly basis, in September, CPI increased by 0.4% month-on-month, while in the same month of 2025, it remained relatively stable; CPIH also increased by 0.4% month-on-month, but in the same month of 2025, it only increased by 0.1%. The year-on-year growth rate is affected by both the prices this month and the base from the same period last year, so a "year-on-year increase" cannot simply be interpreted as all goods suddenly seeing price hikes in September. The National Bureau of Statistics pointed out that transportation, especially automobile fuel, contributed the most to the annual rate changes of CPI and CPIH; however, prices in the catering and hospitality sectors provided the greatest counterbalance. Inflation is the result of a basket of prices, and different items can move in opposite directions within the same month.
Before the release of this data, the UK just saw new labor market figures. Employment, wages, and prices collectively affect residents' purchasing power, as well as discussions regarding interest rates. However, any single-month inflation data is not sufficient to infer how the Bank of England will vote at its next meeting. Especially when prices such as fuel can fluctuate with international markets, policymakers usually need to distinguish between a temporary external price shock and more persistent effects on wages and service costs. Readers may be concerned about interest rates, but they should not interpret a statistical table as a definite indication of a rate cut or hike.
Fuel is the main driving force; the core issue with service prices is not limited to gas stations.
The detailed information provided by the National Bureau of Statistics is more noteworthy than the single figure of 3.5%. Excluding energy, food, alcohol, and tobacco, the core CPI saw a year-on-year increase of 2.8%, higher than the 2.6% in August; the annual rate of CPI service prices rose from 3.4% to 3.7%. The annual rate of CPI commodity prices also increased from 2.7% to 3.2%. These figures indicate that fuel is a prominent source of this upward trend, but it cannot be said that "there is no pressure at all except for energy." Both the core and service sectors have also seen increases, although the extent and causes of these increases require further analysis.
If we only look at the overall CPI, there can be significant differences in family experiences. People who commute by car are more sensitive to fluctuations in fuel prices, while those who primarily use public transportation are affected in different ways; changes in expenses for traveling or dining out may also differ from the average prices of food and lodging items in statistical tables. Statistical indices measure the overall change in a basket of goods and services and do not necessarily equal the bill of a particular family. For families whose wages have not increased in tandem with inflation, even if the overall inflation rate is lower than past peaks, the price level is still higher than before; "a slower increase" does not mean that "prices have returned to their original levels."
The cost of owning a home, represented by CPIH, increased by 3.6% year-on-year in September, while the core CPIH rose by 3.1%, both showing a 0.3 and 0.2 percentage point increase from August respectively. Housing costs are one of the key differences between CPIH and CPI, and they are of reference value when discussing long-term living costs. However, the target measure commonly cited by the Bank of England and the market is CPI. If reports switch between these measures within the same paragraph without explaining the differences, it can lead to contradictions in the data presented. This time, since both indicators are moving in the same direction, their respective definitions and values should still be maintained.
There is still a time lag in the impact of energy on inflation. Fuel prices may quickly be reflected in transportation costs, while it usually takes longer for freight rates and business input costs to be passed on to the prices of goods and services, which may also be absorbed by corporate profits or competition. What the statistical bureau confirms is the price changes in September and their contribution; it does not prove that each subsequent month will follow the same trend. When observing the data for October and beyond, the key points are whether the fuel-driven increase will subside, and whether core and service items will continue to rise.
The significance of interest rates and the pound sterling depends on whether subsequent data can confirm the trend.
The market often links inflation that exceeds expectations with a re-pricing of interest rate forecasts, but this step requires caution. Firstly, whether it is 'higher than expected' must be based on a clear survey sample and time point, and cannot be replaced by the predictions of any single institution with the market consensus. Secondly, the Bank of England takes into account employment, wages, growth, and inflation expectations simultaneously; the central bank's decisions and meeting minutes are the primary sources for policy judgment. What can be confirmed from this article is the September figures published by the statistical office, and it does not indicate that the central bank has already provided new interest rate guidance.
The choices faced by businesses are no less complex. Whether they can raise prices when transportation and raw material costs increase depends on orders, competition, and consumers' affordability. The food service and hospitality sectors have become the biggest factors contributing to price reductions this month, but this does not mean that the entire industry has entered a period of price cuts, nor does it indicate that the pressures on all service industries have eased. Service prices are still showing an annual upward trend, suggesting that it is necessary to analyze different components separately. Retail, logistics, tourism, and manufacturing companies have distinct cost structures, and therefore, a one-size-fits-all conclusion regarding the impact of inflation (whether positive or negative) cannot be applied to them.
For ordinary readers, to determine whether there will truly be a cooling down in the future, they can pay attention to three types of signals: first, the change in the base number when comparing the monthly CPI with the same period last year; second, the prices of core and service items to see if the pressure is spreading from oil prices; third, wages and employment to judge whether household income can cover the continuously rising prices. Looking only at the year-on-year comparison for one month can easily lead to mistaking a short-term rebound for a new round of general inflation, and it can also lead to the mistaken assumption that the problem has ended when there is a decline in the following month.
September's data presented a clear but limited fact: overall inflation in the UK has risen again, with fuel costs being the main driving force, and core inflation as well as inflation measured by services also showing an increase. This data delays the easy conclusion that "inflation has steadily declined," but it cannot alone determine the policy path. Whether this trend will continue will need to be verified by data over several consecutive months and formal judgments from the central bank.
Source: Office for National Statistics, UK, “Consumer price inflation , UK : September 2026”, October 21, 2026. https :// www.ons.gov.uk / economy / inflationandpriceindices / bulletins / consumerpriceinflation / september2026