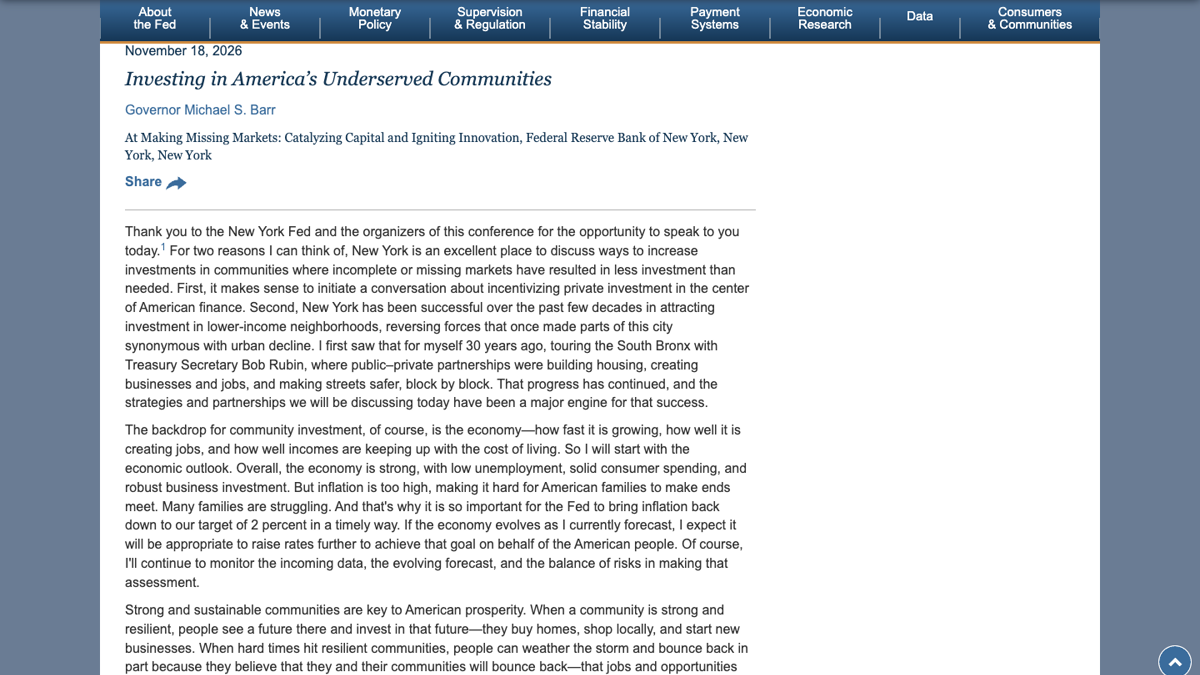


Federal Reserve Board member Michael Barr stated on November 18 that if the economy develops as currently predicted, he expects further interest rate hikes to be appropriate. In his speech, he also mentioned that although the economy is strong and the unemployment rate is low, inflation is too high, and many families are still struggling to manage their finances.
This statement was made at a community investment meeting of the Federal Reserve Bank of New York. Bar linked the 2% inflation target to the cost of living for families, without announcing any new interest rate decisions or specifying the magnitude or timing of any rate hikes. He clearly reserved the option to continue re-evaluating based on new data, changing forecasts, and shifting risk balances.
A strong total volume does not mean that every company is thriving financially.
Bal's description of a balanced economy includes steady consumption, strong corporate investment, and low unemployment. At the same time, he pointed out that wealthy families are in a better situation, while middle- and low-income families are under pressure, and some communities have been left behind by growth. These two assessments coexist in the same speech; one cannot simply summarize his policy stance as 'strong economy.'
The estimates he cited show that 44% of Americans live in low-income communities, where the definition is that at least one-fifth of the residents live below the poverty line. The 44% refers to the proportion of people living in these areas and should not be confused with the overall poverty rate of the American population; the latter figure of at least 20% describes the proportion of poor people within those communities.
Barr also cited a recent consumer finance survey by the Federal Reserve, stating that most households have very little wealth. Low-wealth households are nearly four times as likely to be unable to obtain financial help from relatives and friends, or to be unable to provide help to them, compared to other households. This reflects a difference in mutual assistance capabilities, and the speech did not convert this into personal account balances or a unified number of days of savings.
He discusses how these impacts resonate within communities: the scarcity of jobs and opportunities erodes family and neighborhood ties. For those who analyze American consumption, the significance of this information lies in the need to consider both overall resilience and the buffering capacity of families separately; the speech does not provide sufficient data to estimate consumer growth in the next quarter or the profits of certain consumer-related stocks.
What banks may lack is local information.
The speaker then turned to discuss why private capital has not flowed sufficiently into certain regions. The obstacles listed by Barr include information asymmetry: commercial banks may find it difficult to identify opportunities in low-income areas. Community development financial institutions, namely CDFI, as well as local and national organizations, can help reduce the cost of understanding the circumstances of borrowers and their communities.
Cooperation may also involve coordinating lending to address the issue of difficulty in synchronizing actions among multiple parties, and by sharing risks, it can reduce banks' exposure. According to his explanation, the role of public-private cooperation is not merely to add a sum of money, but also to establish a financing foundation that allows projects to enter a long-term investment phase.
For readers who pay attention to bank stocks and credit risks, this can help them understand the business logic of community finance: local partners hold the information, while banks provide credit and services. How the risks are shared determines whether the cooperation can be successful. Bar has not disclosed the default rates, bank yields, or capital occupation of these projects; therefore, policy support cannot be directly equated with increased bank profits.
He specifically mentioned that different types of banks were involved, including national large banks, regional banks, banks with specialized business models, and community banks. The Community Reinvestment Act is seen by him as providing foundational support, while CDFI often acts as local financial providers that connect different participants.
Three projects, corresponding to three types of funding sources.
The City Point project in Brooklyn, New York, combines supermarkets offering a full range of services with 120 affordable housing units and retail spaces for local small businesses. Barr uses this example to illustrate how new market tax credits can leverage private investment in communities. He says he played a role in promoting this mechanism and mentioned that Congress recently made it permanent.
Another example is in Middletown, New York: a long-idle historic train station has been transformed into a community center that includes a Head Start project for children, in response to the scarcity of local child care options. Part of the financing comes from new market tax credits; however, the total cost of the project was not mentioned in the speech.
Syracuse, on the other hand, established a revolving loan fund for mixed-income housing. The seed capital listed by Barr is 30 million dollars, with private partners providing the remaining 120 million dollars. Adding these two amounts together, the total is 150 million dollars; this is a simple calculation in this article, and the original text does not use it to estimate the fiscal multiplier or the number of additional houses that will be built in the future.
He also mentioned that tax credits for low-income housing have helped to create or preserve nearly 4 million units of housing over the past 40 years. The terms "create or preserve" must be kept together; they cannot all be considered as new supply. Such long-term cumulative results cannot be directly compared with annual data on housing starts.
These examples illustrate how capital enters communities that have long lacked investment, while the statement on interest rate hikes appears in the initial economic outlook section. Readers should distinguish between personal policy preferences, project cases, and decisions already made by the committee; this material does not change the range of federal funds rates.
Therefore, the next criterion for judgment is to observe whether the conditions mentioned by Barr have changed: whether the new data has altered his economic forecasts and risk assessments. The long-term arrangements for community investment are still being pursued, while his assessment of inflation has clearly indicated that further tightening may be necessary; each of these aspects entails different policy tasks.