Recent sell-offs have been driven by concerns about intensifying competition in China. In China, memory chip manufacturer ChangXin Memory ( CXMT ) announced a technology that could increase the density of DRAM and challenge existing manufacturers. At the same time, investors are also worried whether the boom in artificial intelligence spending has gone too fast; CoreWeave is a typical example, with its rising debt and high infrastructure costs sparking concerns about the sustainability of such investments.
"I think we can expect a breakthrough next month, as repurchases may accelerate," Hunting Alphas stated.
Time points are particularly important, as Micron Technology's restrictions on stock repurchases under the U.S. CHIPS Act funding agreement will be relaxed after December 9th. These restrictions were initially set in place to ensure that federal subsidies were used to support domestic chip manufacturing, rather than to distribute funds to investors; current rules basically only allow repurchases to be used to offset employees' stock compensation. Although some restrictions will still remain, the upcoming changes may allow Micron to use more free cash flow for stock repurchases. The company's board of directors has increased the total repurchase authorization from $1 billion to $35.16 billion, and the expanded plan will take effect on December 9th, which could also provide another catalyst for the stock price.
Apart from the potential buying interest that may emerge in December, Hunting Alphas believes that there are several reasons to remain optimistic about Micron's long-term prospects. It is expected that by 2028, storage supply will continue to be tight, while artificial intelligence applications will require an increasing demand for DRAM, NAND, and high-bandwidth products. This imbalance may support manufacturers that supply the world's largest technology customers in maintaining favorable pricing environments, as well as keeping their profit margins relatively high.
Another positive development is that Micron is working hard to secure multi-year supply agreements, some of which extend beyond 2030. Hunting Alphas believes that these arrangements may strengthen customer relationships and ultimately boost the company's global DRAM market share to a high range of over 20%.
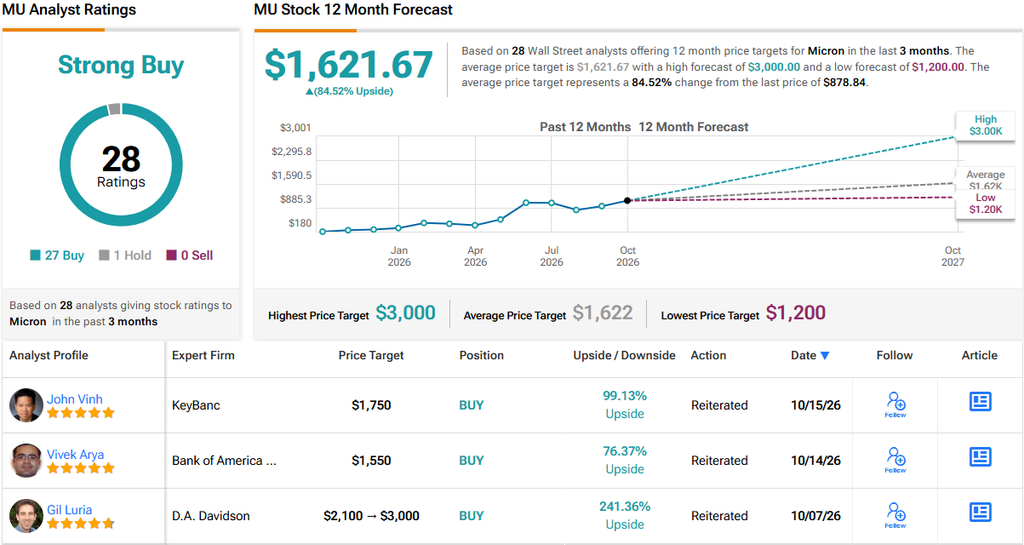
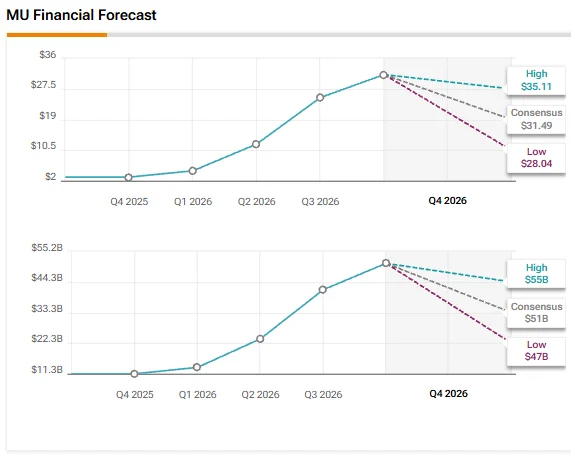
However, this investor also acknowledges that if the semiconductor cycle peaks earlier than expected, Micron's valuation leaves little room for disappointment. Current Wall Street forecasts indicate a possible slowdown in earnings for the fiscal year 2028, which has raised concerns among the market about whether current expectations can withstand a weaker industry environment.
"However, I am willing to take this risk because from the perspective of business momentum and management's outlook, there is still no visible sign of a cycle peak," Hunting Alphas explained.
This confidence also extends to the technical aspect of the stock. The investor believes that the decline in trading volume during the consolidation period indicates that the recent weakness may just be a temporary pause. Hunting Alphas thinks that there is almost no evidence at present to suggest that this round of adjustment will evolve into a lasting reversal, but it will ultimately be tested over the next few months.
Currently, December presents Micron investors with a specific event to watch. If buybacks accelerate while memory chip pricing remains favorable, Hunting Alphas believes the latest sell-off may ultimately prove to be an opportunity missed by investors due to excessive caution. Therefore, this investor gives MU stock a "buy" rating. (Click here to view the historical performance of Hunting Alphas)